
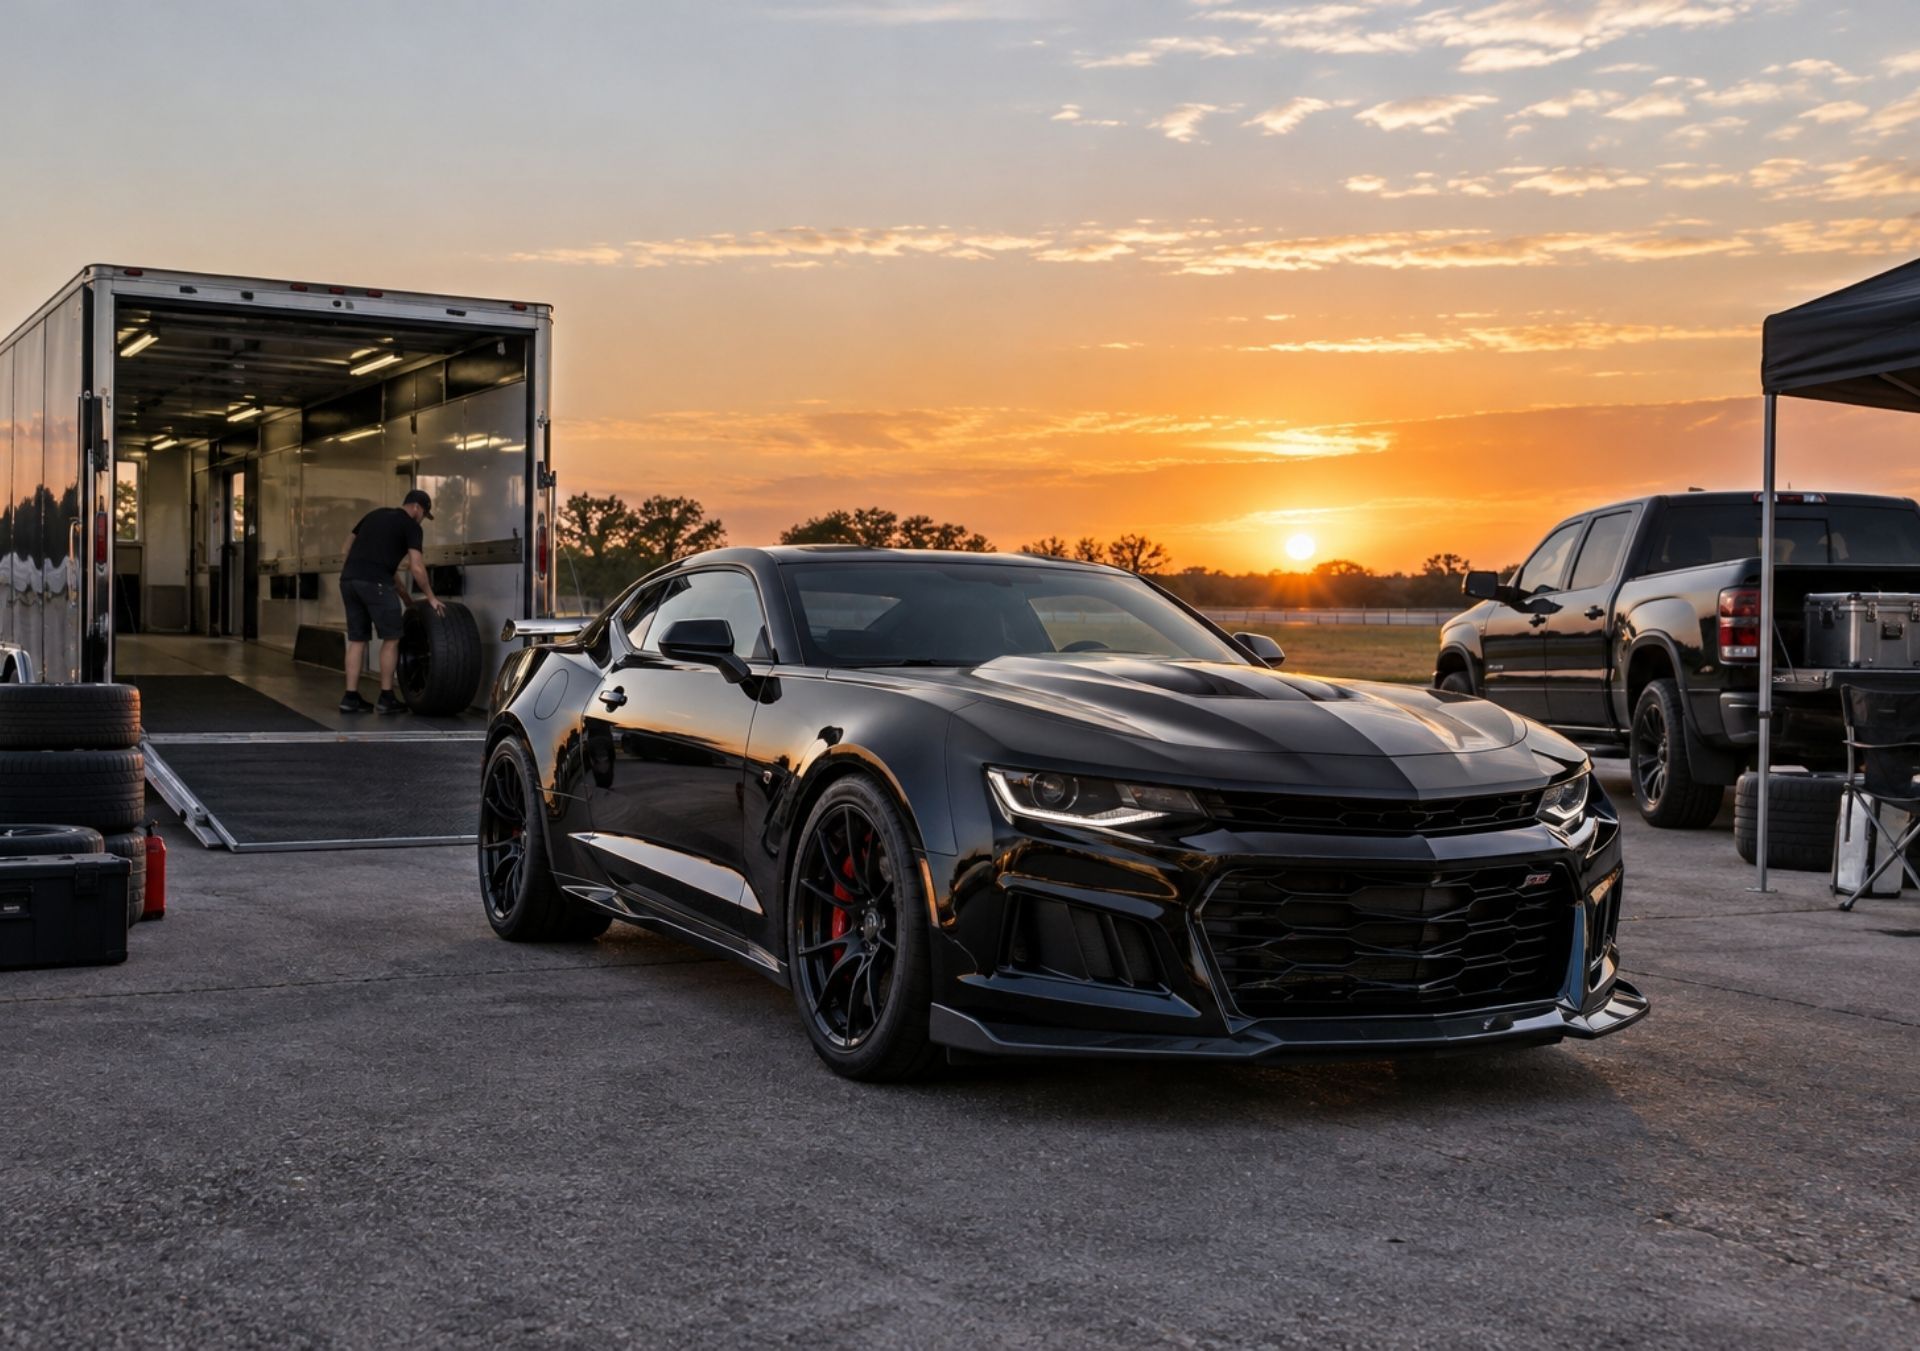
A Hennessey-tuned vehicle isn't just a car with a few bolt-on parts. It's a purpose-built machine carrying tens of thousands of dollars in engineering upgrades, from supercharger systems and custom exhaust to ECU recalibrations that push horsepower well beyond factory specs. Hennessey Performance
broke ground on an advanced manufacturing facility to keep pace with growing demand, a clear sign that these builds are becoming more popular and more valuable. If you own one of these vehicles in Texas, your insurance needs to match the investment.
Standard auto policies weren't designed for cars like these, and the
coverage gaps can cost you dearly after a loss. Getting the right protection means understanding
agreed value endorsements, repair choice provisions, transport coverage, and storage options built specifically for
high-performance builds.
The Need for Specialized Insurance for Texas Hennessey Builds
Hennessey Performance vehicles occupy a unique space between production cars and full custom builds. The company celebrated its 35th anniversary in 2026 with the limited-edition Super Venom Mustang, a build featuring over $37,000 in aftermarket upgrades on top of the base vehicle price. That kind of modification investment demands insurance that actually recognizes and protects the full value of the car, not just the factory sticker.
Why Standard Auto Policies Fail High-Performance Vehicles
Most standard auto policies calculate payouts based on what a "comparable vehicle" would sell for on the open market. The problem is, there's no comparable vehicle for a Hennessey VelociRaptor 600 or a tuned Cadillac CT5-V Blackwing with 1,000+ horsepower. Your insurer's claims system sees a Ford or a Cadillac, not a $150,000 performance machine.
Standard policies also tend to exclude or severely limit coverage for aftermarket modifications. You might get $1,000 to $2,000 toward non-factory parts, which doesn't even cover a Hennessey intake system. If your car is totaled, you're left holding the bill for the performance gap between what your policy pays and what you actually spent.
The Hennessey Premium: Protecting Aftermarket Modifications
The real cost of a Hennessey build sits in the modifications themselves: the supercharger kit, the upgraded drivetrain components, the custom calibration work. A specialty policy designed for high-performance vehicles treats these modifications as part of the vehicle's insured value, not as optional accessories.
Texas has a strong aftermarket culture, and the state's
specialty insurance market for rare and modified automobiles has grown to meet that demand. Working with an insurer who understands the difference between a bolt-on exhaust tip and a fully integrated forced-induction system means your policy actually reflects what sits in your garage.
Agreed Value vs. Actual Cash Value
This is the single most important coverage distinction for any Hennessey owner. The difference between agreed value and actual cash value can mean tens of thousands of dollars in a total loss scenario.
Locking in the Investment Price
An agreed value policy sets a specific dollar amount for your vehicle at the time the policy is written. You and the insurer agree that the car is worth, say, $185,000, and that's what gets paid in a covered total loss. No haggling, no market adjustments, no depreciation formulas.
To lock in this value, you'll typically need a professional appraisal from someone familiar with high-performance builds. For a Hennessey vehicle, that means an appraiser who can evaluate the specific upgrade package, the labor involved, and the current market for comparable builds. Plan on getting this appraisal updated every two to three years, since the market for these vehicles shifts as new models and limited editions come out.
Avoiding Depreciation Disputes After a Loss
Actual cash value policies use depreciation schedules that treat your Hennessey the same way they'd treat a stock sedan. A three-year-old vehicle might lose 30-40% of its value on paper, even though the Hennessey modifications have held or increased in value. The catch is that ACV policies let the insurer decide what your car is worth after the loss, when you have the least bargaining power.
Agreed value eliminates this fight entirely. You've already settled on the number. If your VelociRaptor is stolen from a Houston parking garage or damaged beyond repair in a
hailstorm near San Antonio, the payout matches your actual investment.
Coverage Comparison: Standard vs. Hennessey-Specific Policies
Here's a side-by-side look at where standard and specialty policies diverge for a Hennessey build:
| Coverage Feature | Standard Auto Policy | Hennessey-Specific Specialty Policy |
|---|---|---|
| Valuation Method | Actual cash value (depreciated) | Agreed value (pre-set amount) |
| Aftermarket Parts | $1,000-$2,000 limit typical | Full modification value included |
| Repair Shop Choice | Insurer's preferred network | Owner selects certified shop |
| Parts Used in Repairs | Aftermarket/generic allowed | OEM or Hennessey-spec parts required |
| Transport Coverage | Typically excluded | Enclosed trailer transit included |
| Storage/Lay-up Discount | Not available | Reduced rates during non-use periods |
| Mileage Restrictions | None (standard daily driver) | Annual mileage caps with lower premiums |
The premium difference between these two policy types is real, but so is the coverage gap. Paying an extra $800-$1,500 per year for a specialty policy looks like a bargain when you're facing a $40,000 shortfall on a total loss claim.
Maintaining Performance Integrity with Repair Choice
A fender bender on a stock truck is an inconvenience. The same fender bender on a Hennessey-tuned truck can turn into a mechanical nightmare if the wrong shop handles the repair. Your insurance policy's repair provisions matter as much as the dollar amount on your declarations page.
Selecting Certified High-Performance Technicians
Most insurers steer you toward their preferred body shops, which are chosen for cost efficiency rather than technical expertise. These shops may do fine work on standard vehicles, but they're unlikely to understand the tolerances and specifications of a Hennessey build.
A specialty policy with a repair choice provision lets you select the shop. For Texas Hennessey owners, that might mean sending the vehicle back to Hennessey's facility in Sealy, or to a certified performance shop in Dallas or Houston that has experience with forced-induction systems and upgraded suspension components. The rising cost of parts, equipment, and specialized technology makes it even more critical that your insurer covers the actual expense of proper repairs, not just the cheapest estimate.
OEM and Hennessey-Specific Part Replacement
Standard policies often allow insurers to approve aftermarket replacement parts, which is ironic when the entire vehicle is an aftermarket build. If your Hennessey supercharger housing gets damaged, you don't want a generic part bolted in its place.
A proper performance vehicle policy specifies OEM or manufacturer-equivalent parts. For Hennessey vehicles, this means components that meet the original build specifications. This isn't just about aesthetics. Incorrect parts on a high-horsepower vehicle create reliability and safety risks that can cascade into much larger problems.
Protection Beyond the Pavement: Transport and Storage
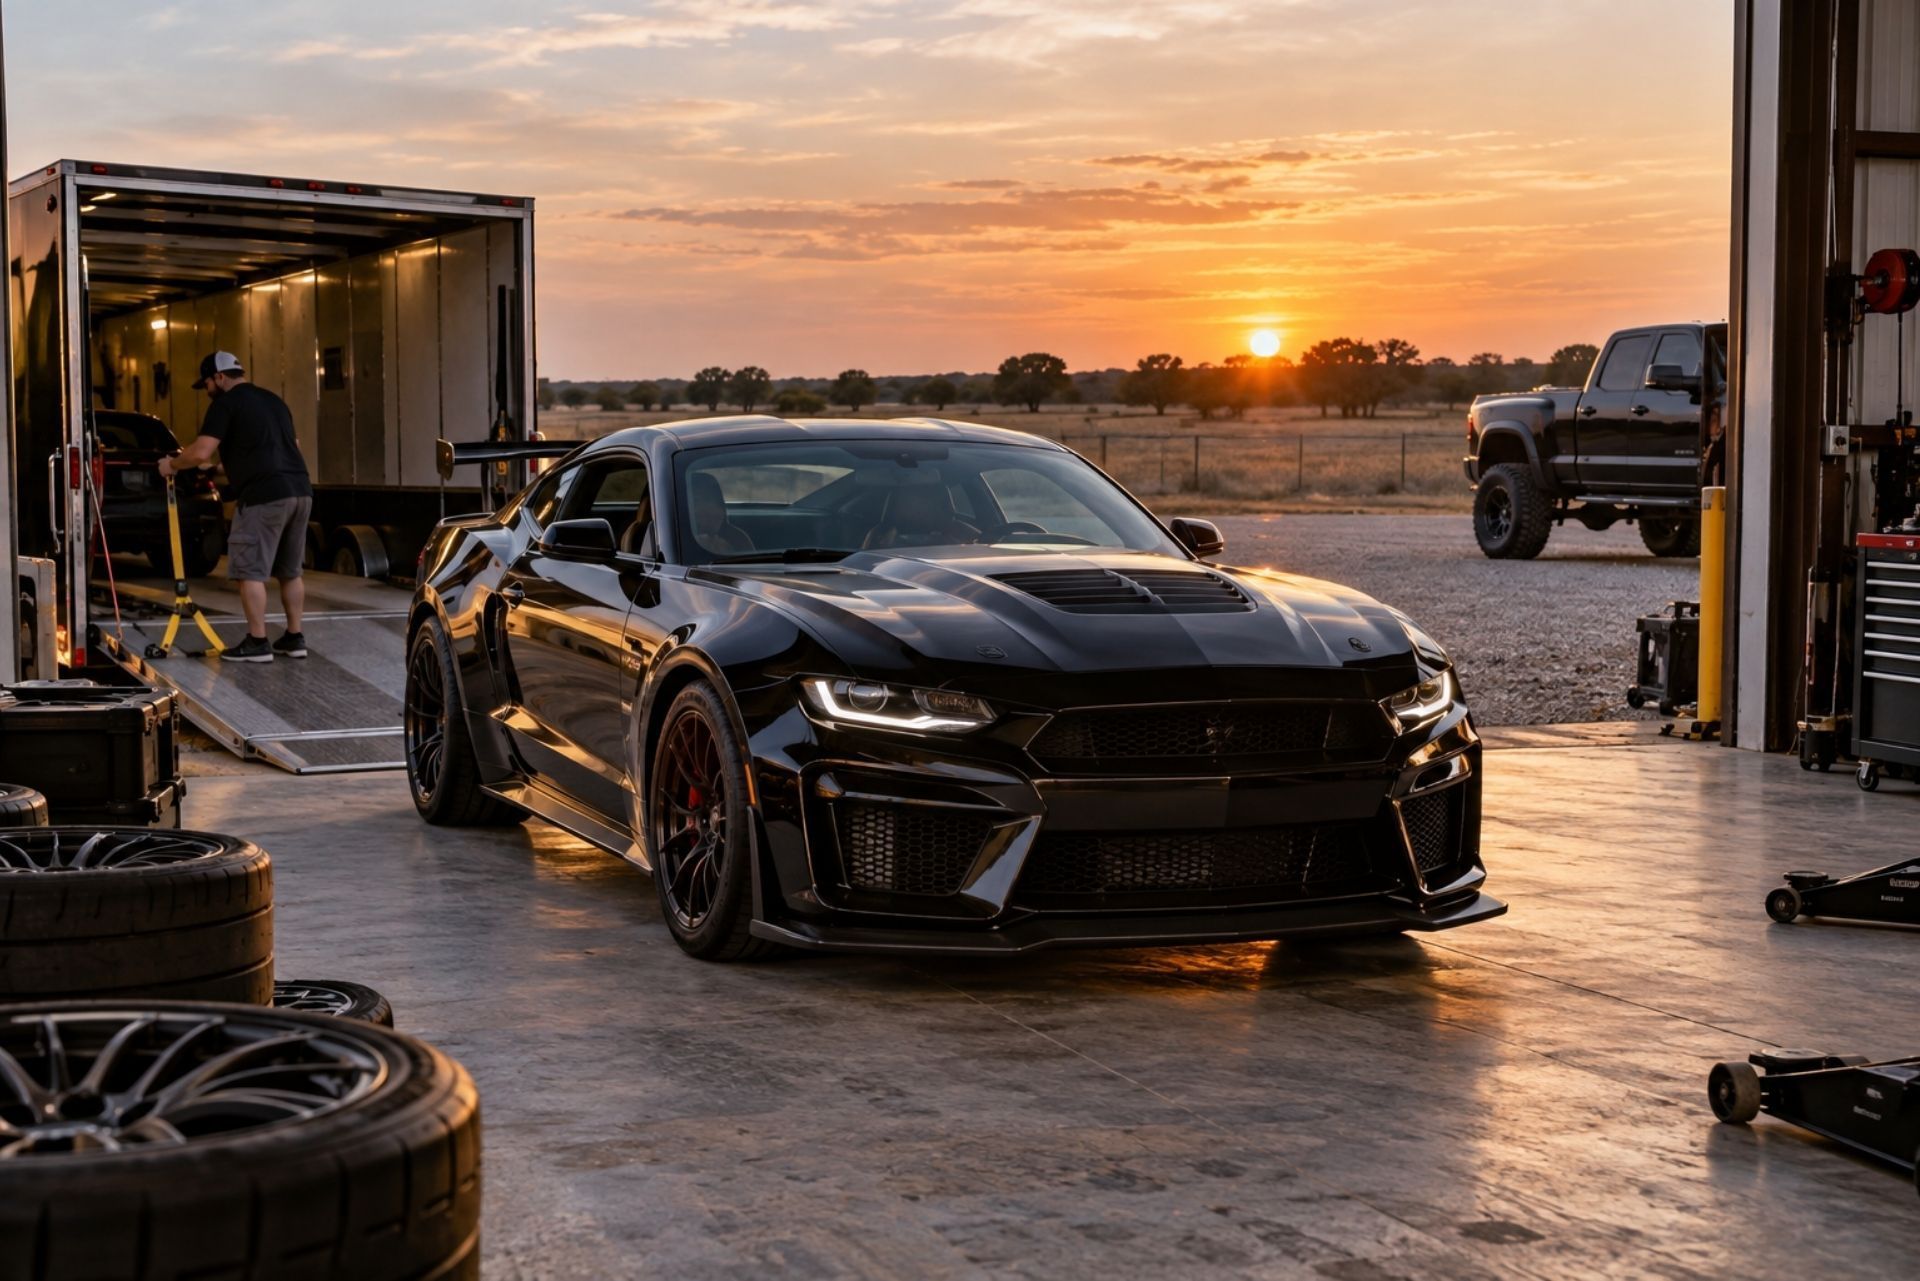
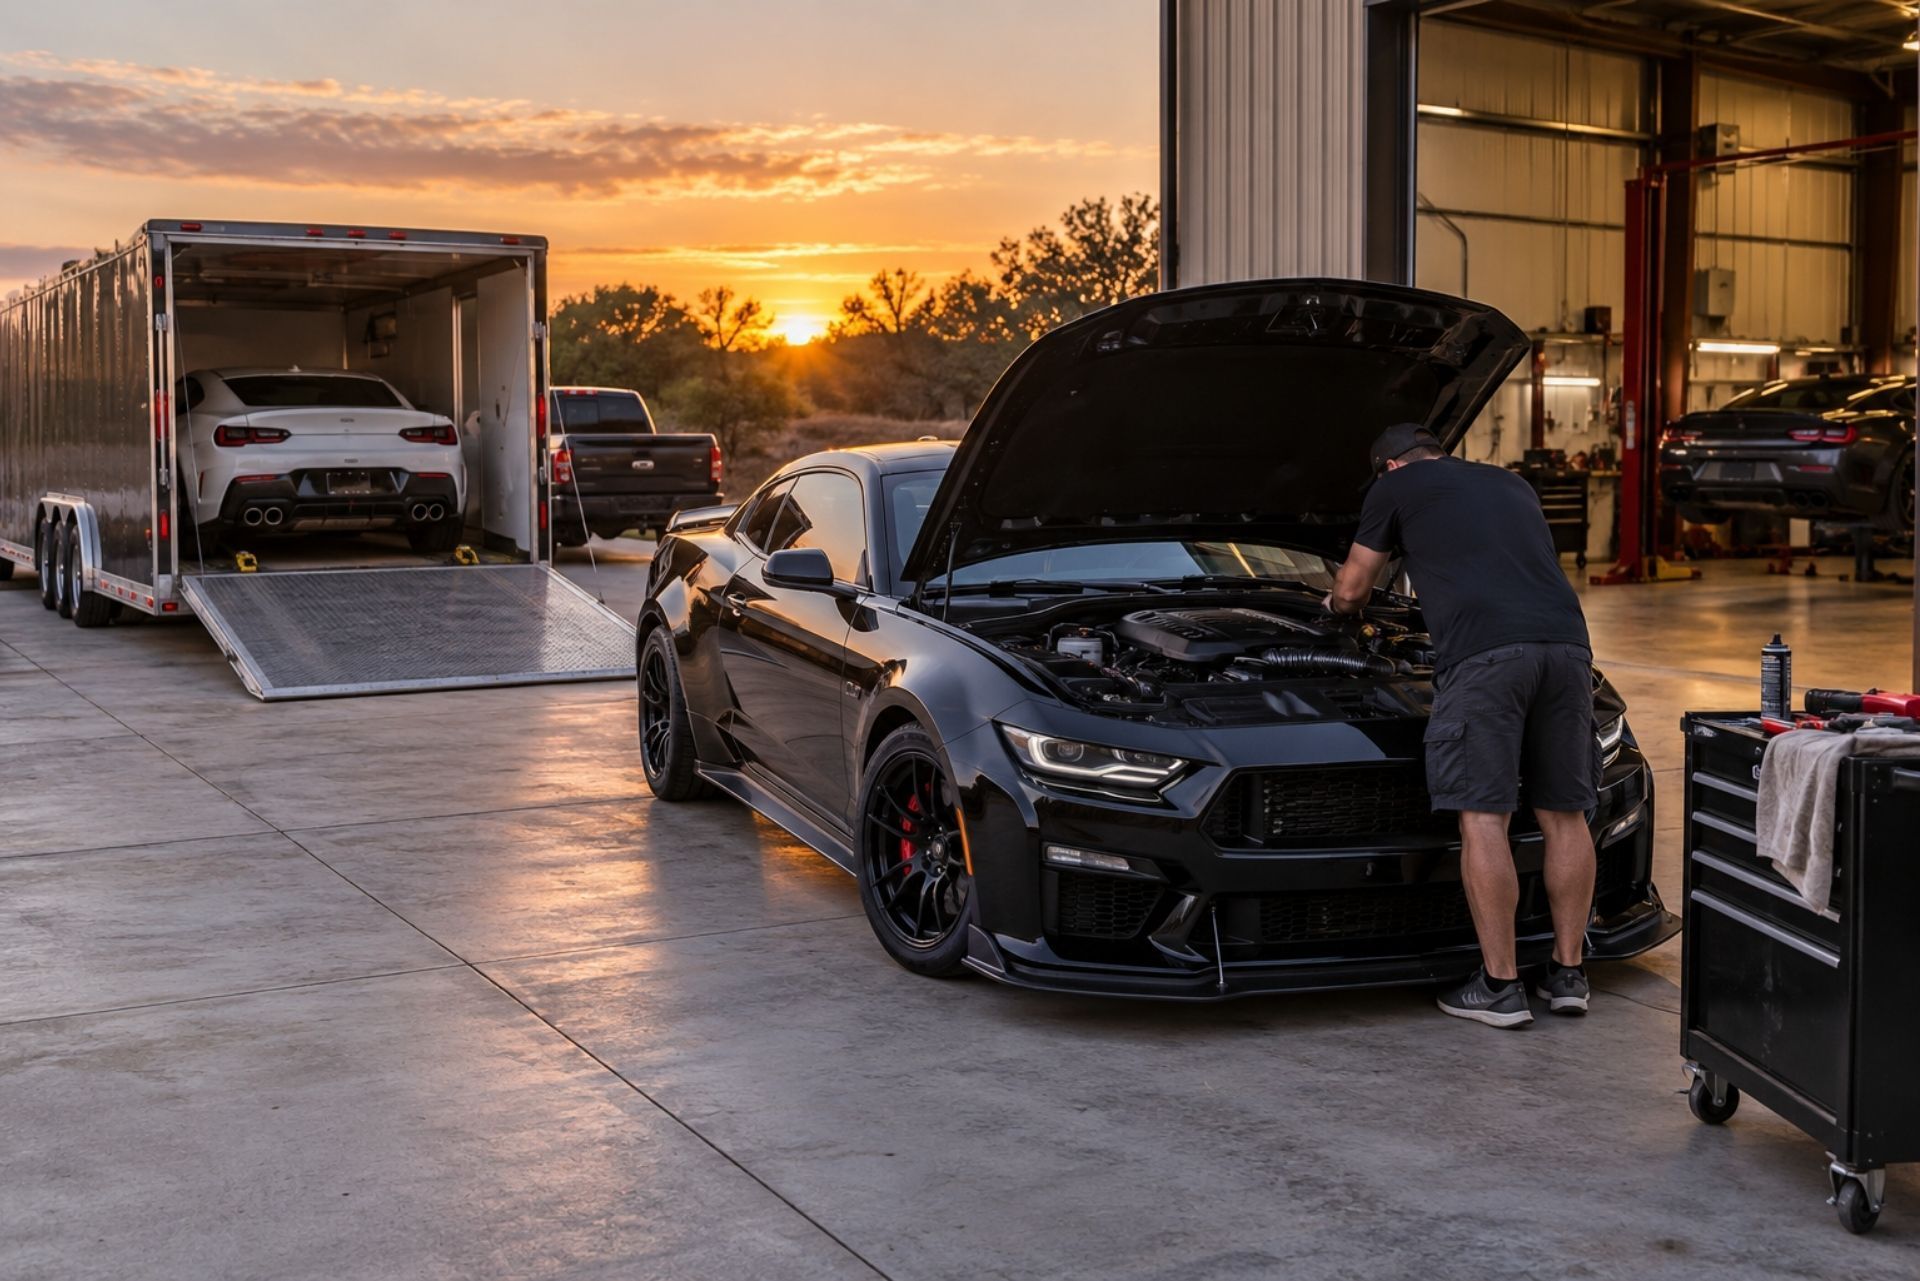
Your Hennessey doesn't just sit in the driveway. It goes to car shows, track days, and sometimes across the state for service. The miles between your garage and the destination are some of the riskiest your vehicle will face.
Enclosed Trailer Coverage During Transit
Open transport exposes your vehicle to road debris, weather, and the carelessness of other drivers. Most Hennessey owners use enclosed trailers for exactly this reason, but your standard auto policy likely doesn't cover the vehicle while it's on a trailer.
Specialty policies include transit coverage that protects your vehicle during enclosed transport, whether you're hauling it yourself or using a professional carrier. This matters if you're heading from Austin to a show in Dallas or shipping the vehicle to Hennessey's shop for a scheduled upgrade. Texas requires vehicle storage facilities to be licensed through the Texas Department of Licensing and Regulation, and your insurer should verify that any third-party storage or transport provider meets state requirements.
Lay-up Periods and Garage Storage Discounts
Many Hennessey owners don't drive their builds daily. If your car spends five or six months a year in climate-controlled storage, you shouldn't be paying full premiums during those months.
Lay-up provisions reduce your coverage (and your premium) during storage periods. You maintain comprehensive coverage for fire, theft, and weather damage, but drop collision and liability since the vehicle isn't on the road. Some Texas specialty insurers offer 30-50% premium reductions during lay-up periods. One thing to keep in mind: your storage facility should maintain stable temperature and humidity levels, ideally between 55-75°F with humidity below 50%, to prevent moisture damage to electronics and upholstery.
Common Questions About Hennessey Insurance
Do I need a separate policy for my Hennessey, or can I add it to my existing auto insurance? Most standard carriers can't properly cover a Hennessey build even with endorsements. A standalone specialty policy from a carrier experienced with high-performance vehicles is usually the better option.
How often should I get my Hennessey appraised for insurance purposes? Every two to three years, or whenever you add significant modifications. Keep detailed records of every upgrade, including invoices, part numbers, and installation photos.
Does Texas have any specific laws affecting modified vehicle insurance? Texas has been considering legislation related to vehicle modification standards, and the state's inspection requirements apply to modified vehicles. Your insurer should be familiar with Texas-specific regulations for aftermarket builds.
Will my premium go up if I track my Hennessey? Most specialty policies exclude track use unless you purchase a separate track day endorsement. Some carriers offer this as an add-on for an additional premium. Don't assume your policy covers you at the track without checking.
What documentation do I need to file a claim on a Hennessey vehicle? Have your agreed value appraisal, build sheet from Hennessey, all modification invoices, and a current photo inventory ready. File the claim within 24-72 hours of the incident and request a claims adjuster experienced with modified vehicles.
Can I insure a Hennessey build that's still in progress? Some specialty carriers offer "builder's risk" or in-progress coverage. The vehicle's value is adjusted as modifications are completed, with the final agreed value set once the build is finished.
Making the Right Choice for Your Vehicle
Protecting a Hennessey Performance vehicle in Texas requires insurance that matches the thought and investment you've put into the build. Agreed value coverage eliminates depreciation fights and guarantees your payout reflects the real worth of the car. Repair choice provisions keep your vehicle in the hands of technicians who understand it. Transport and storage coverage fills the gaps that standard policies ignore entirely.
Start by getting a professional appraisal of your current build. Document every modification with photos, receipts, and serial numbers. Then talk to a specialty insurer who works specifically with high-performance and modified vehicles in Texas, not a general agent who'll try to fit your 1,000-horsepower build into a standard policy template.
Your Hennessey represents years of planning and a serious financial commitment. The right insurance policy protects all of it, from the supercharger to the last custom badge, whether the car is on the highway, on a trailer, or tucked away in your garage.
About The Author: Aaron Husman
As COO of The Phoenix Insurance, I’m focused on building lasting client relationships and delivering insurance solutions that make protection simple and effective. With years of experience in commercial and personal insurance, I take pride in helping individuals and businesses find coverage that brings confidence and peace of mind.
customer reviews
See What Our Clients Say About Us
Types of Auto Insurance
Insurance For Car Collectors By Car Collectors
Our team specializes in providing tailored insurance coverage for car collectors. Whether you own a rare classic, an exotic beauty, or a powerful muscle car, we understand the unique needs of your collection and work to ensure it’s protected with the care and expertise it deserves.



Contact us for better help and services. Explore all types of car insurance
FREQUENTLY ASKED QUESTIONS
At The Phoenix Insurance, we’re committed to answering your most pressing questions to ensure you feel confident about your coverage. From understanding the benefits of working with an independent agency to the specific insurance options we offer for Texas residents, we’ve got you covered.
What makes The Phoenix Insurance different from other insurance providers?
The Phoenix Insurance is an independent agency, meaning we work with multiple insurance carriers to find the best coverage and rates for your unique needs. Our proactive support and commitment to personalized service set us apart from other providers.
Why should I choose an independent insurance agency in Texas?
Independent agencies like The Phoenix Insurance offer more flexibility and personalized service than large, single-carrier companies. We compare coverage options from top-rated carriers to ensure you get the most value for your money.
Does The Phoenix Insurance provide coverage for real estate investors?
Yes, we specialize in insuring real estate investments, including single-family homes, apartments, commercial buildings, and industrial properties. Our team has extensive experience protecting real estate assets across Texas.
How does The Phoenix Insurance handle claims?
We guide clients through the entire claims process, working directly with the insurance carrier to ensure quick and fair resolutions. Our team is dedicated to providing the support you need when it matters most.
What types of insurance does The Phoenix Insurance offer for Texas residents?
We offer a wide range of personal and business insurance options, including home, auto, umbrella, and recreational vehicle coverage for individuals, as well as liability and property insurance for businesses and real estate investors.
Insurance Knowledge. Stories. Tips.
Our Latest Blogs
Explore expert tips, industry insights, and helpful resources from The Phoenix Insurance to stay informed and make confident decisions about your coverage.


Contact Us