
A $3,500 e-bike vanishing from your garage or a split-second collision with a pedestrian on a crowded Austin trail can turn a great investment into a financial headache overnight. Texas riders face real risks, from theft in urban centers like Houston and Dallas to
liability exposure on shared-use paths, and most don't realize their existing insurance leaves major gaps. Understanding your options for e-bike insurance in Texas, including theft, physical damage, liability, and
medical payments coverage, is the difference between absorbing a painful loss and riding with genuine peace of mind. With e-bike sales continuing to climb in 2026, the stakes have never been higher. Whether you own a commuter-class pedal assist or a throttle-powered Class 2 model worth several thousand dollars, the right policy structure matters more than you might think.
Understanding Texas E-Bike Classifications and Laws
Texas groups electric bicycles into three classes, and the class your bike falls into affects where you can ride, how fast you can go, and what kind of coverage makes sense. The state's Transportation Code treats e-bikes as traditional bicycles rather than motor vehicles, which means no license, registration, or state-mandated insurance is required. That's a double-edged sword: fewer bureaucratic hurdles, but also fewer built-in protections if something goes wrong.
The Three-Tier Class System in Texas
Class 1 e-bikes provide pedal assist only and cap out at 20 mph. Class 2 bikes add a throttle but keep the same 20 mph speed limit. Class 3 models offer pedal assist up to 28 mph and are restricted to riders aged 15 and older. All three classes must have a label from the manufacturer identifying the class, top assisted speed, and motor wattage. The class designation directly influences where you're allowed to ride and, by extension, your risk profile.
Where You Can Legally Ride Your E-Bike
Class 1 and Class 2 e-bikes are generally permitted on bike paths, multi-use trails, and roads across Texas. Class 3 bikes face more restrictions, often barred from shared-use paths unless a local ordinance says otherwise. One thing to keep in mind:
local municipalities can implement their own rules, like the Town of Prosper, which introduced a local registration requirement in December 2025. Always check your city's specific ordinances before assuming statewide rules are the whole picture.
Protecting Your Investment Against Theft
E-bike theft is a persistent problem in Texas cities. A quality e-bike often costs between $1,500 and $5,000 or more, making it an attractive target. Locked outside a coffee shop in Austin or stored in an apartment complex bike room in San Antonio, your bike is vulnerable in ways a car simply isn't.
Why Homeowners Insurance Often Falls Short
Many riders assume their homeowners or renters policy will cover a stolen e-bike. In some cases, personal property coverage does extend to bicycles, but the limits are often capped well below the bike's actual value. While e-bikes are legally bicycles in Texas, many homeowners insurance policies exclude "motorized vehicles," which can lead to a denial of liability claims if a rider causes injury or property damage (https://www.reyeslaw.com/blog/do-you-need-e-bike-insurance-texas/). There's also the deductible to consider: if your homeowners deductible is $1,000 and your bike was worth $2,500, you're recovering very little after a claim. Worse, filing a claim on your homeowners policy for a bike theft can affect your premiums at renewal.
Full Replacement Value vs. Actual Cash Value
This distinction trips up a lot of policyholders. Actual Cash Value (ACV) pays you what your bike was worth at the time of the theft, factoring in depreciation. If you bought a $4,000 e-bike two years ago, ACV might only pay $2,400. Full Replacement Value, on the other hand, covers the cost of buying the same or equivalent bike at today's prices, no depreciation deducted. For an asset that loses value the moment you ride it off the lot, replacement value coverage is almost always the smarter choice. Ask any prospective insurer which valuation method they use before you sign.
Liability Coverage: Protecting Yourself from Accidents
Theft gets the headlines, but liability exposure is the risk that can truly wreck your finances. Texas doesn't require e-bike riders to carry liability insurance, yet a single accident involving a pedestrian or another cyclist can generate medical bills and legal fees that dwarf the cost of the bike itself.
Bodily Injury and Property Damage Scenarios
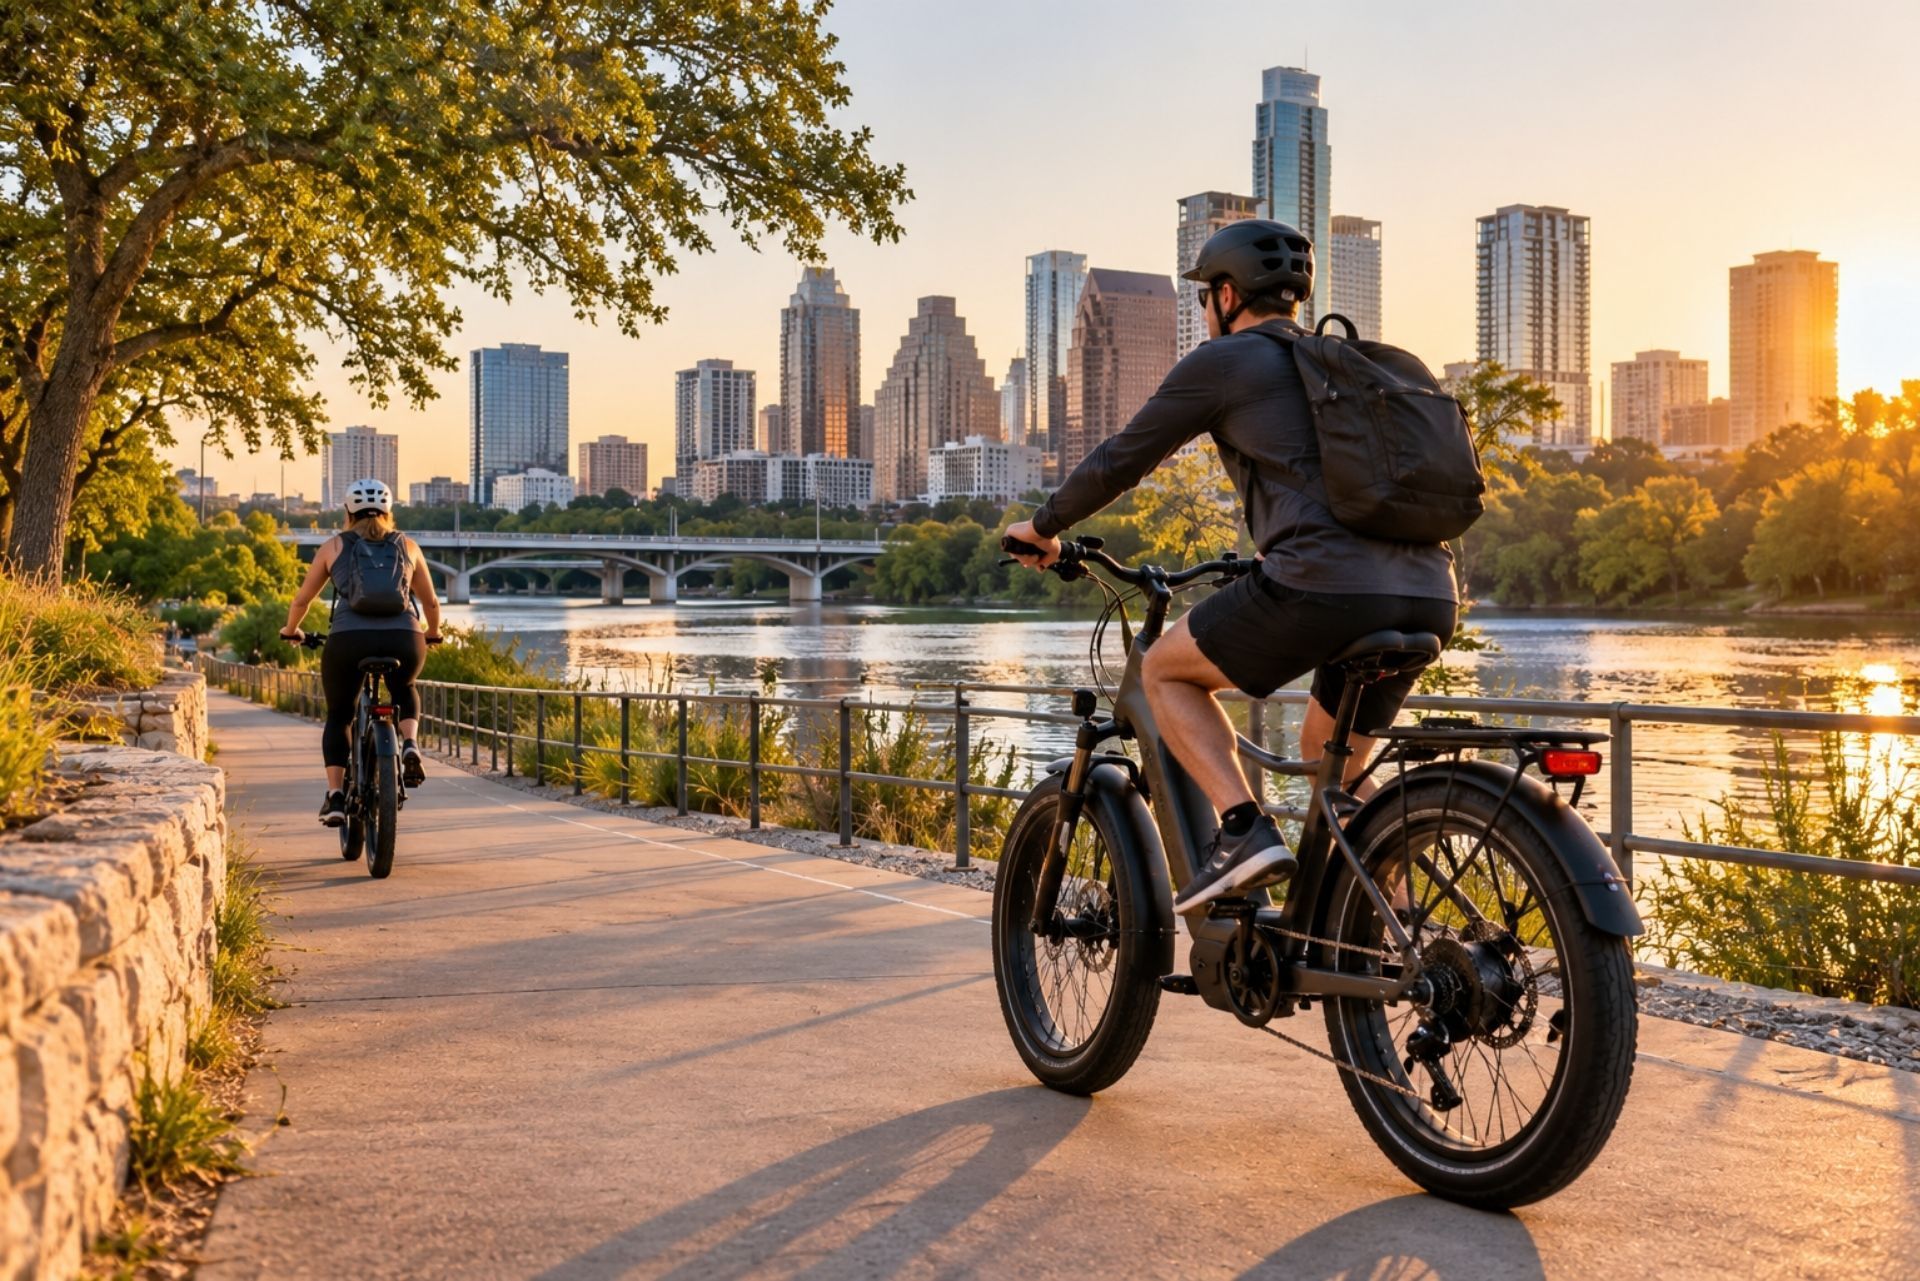
Picture this: you're riding your Class 2 e-bike on a shared path near Lady Bird Lake, and a dog on a retractable leash darts in front of you. You swerve, clip a jogger, and they break a wrist. Medical bills, potential lost wages, and a possible lawsuit land squarely on you. Without liability coverage, you're paying out of pocket. A solid e-bike liability policy covers both bodily injury to others and property damage you cause while riding. This includes legal defense costs if the injured party decides to sue, which happens more often than most riders expect.
Medical Payments for the Rider
Liability coverage protects others, but what about you? Medical payments coverage, sometimes called MedPay, pays for your own medical expenses if you're injured in a riding accident, regardless of who's at fault. This can cover emergency room visits, ambulance transport, X-rays, and follow-up care. It's particularly valuable if you have a high-deductible health plan, since MedPay kicks in without requiring you to meet your health insurance deductible first. For riders commuting daily through heavy traffic in Houston or Dallas, this coverage is worth every penny.
Comparing Coverage: Standard vs. Specialized Policies
The gap between a homeowners endorsement and a standalone e-bike policy is wider than most people realize. Specialty bike insurance has become a distinct category in 2026 because traditional insurance was never designed to address how bikes are actually used today. Commuting, trail riding, and urban errands create exposure patterns that a standard homeowners policy simply doesn't anticipate.
Comparison Table: Homeowners Endorsement vs. Standalone E-Bike Policy
| Coverage Feature | Homeowners Endorsement | Standalone E-Bike Policy |
|---|---|---|
| Theft (away from home) | Limited or excluded | Covered, including from vehicle racks |
| Physical damage (crash) | Typically excluded | Covered for collisions and falls |
| Liability (bodily injury) | May apply under personal liability | Dedicated e-bike liability limits |
| Medical payments (rider) | Not included | Available as add-on or included |
| Accessories and upgrades | Rarely covered | Covered with itemized list |
| Deductible | Often $500-$1,000+ | As low as $150 with specialized providers |
| Impact on home policy premiums | Claim may raise rates | No effect on homeowners policy |
| Valuation method | Actual Cash Value (typical) | Replacement Value (common) |
The standalone policy wins in almost every category. The catch is that it's a separate premium, usually ranging from $100 to $300 annually depending on your bike's value, your location, and the coverage limits you select (https://velosurance.com/faq/ebike-insurance-cost/). For bikes worth $2,000 or more, the math strongly favors a dedicated policy.
Common Questions About Texas E-Bike Insurance
Does Texas require insurance for e-bikes? No. Under the Texas Transportation Code, e-bikes are classified as bicycles, so there's no statewide insurance mandate. That said, carrying coverage is strongly recommended, especially for Class 2 and Class 3 bikes that cost thousands of dollars and travel at speeds where accidents cause real harm.
Will my bike be covered if it's stolen from my car rack? Most specialized e-bike policies cover theft away from home, including from vehicle-mounted racks. You'll typically need to show you used a secondary locking device. Check your specific policy for lock requirements, as some insurers require a U-lock or chain rated above a certain security level.
Does insurance cover the battery if it fails? Standard e-bike insurance covers the battery if it's damaged in a crash or stolen along with the bike. It won't cover natural wear and tear or electrical failure from poor maintenance. Replacing an e-bike battery typically costs between $400 and $900, so keeping maintenance records helps if you ever need to prove a covered loss versus a wear issue (https://www.hovsco.com/blogs/news/e-bike-battery-replacement-cost-guide).
Am I covered if I hit a pedestrian?
Yes, if you carry liability coverage. This is exactly what liability insurance is built for: paying the injured person's medical bills and covering your legal defense if a lawsuit follows. Without it, you're personally responsible for every dollar, and pedestrian injury claims in Texas can easily reach five figures.
Making the Right Choice for Your Ride
Texas e-bike insurance covering theft, physical damage, liability, and medical payments isn't a luxury. It's a practical decision that protects both your bike and your bank account. The state won't make you buy a policy, but the financial exposure from a single theft or accident can far exceed the annual cost of coverage.
Start by documenting your bike: take photos, save the receipt, and record the serial number. Get a professional appraisal if your e-bike is worth $3,000 or more, and update it every two to three years as component values shift. Then compare at least two or three standalone e-bike policies side by side, paying close attention to deductibles, valuation methods, and whether away-from-home theft is included.
Your e-bike is likely one of the more expensive things you own that regularly sits outside, unattended. Treat its insurance with the same seriousness you'd give your car or your home. A few hundred dollars a year is a small price for knowing you're covered when it counts.
About The Author: Aaron Husman
As COO of The Phoenix Insurance, I’m focused on building lasting client relationships and delivering insurance solutions that make protection simple and effective. With years of experience in commercial and personal insurance, I take pride in helping individuals and businesses find coverage that brings confidence and peace of mind.
customer reviews
See What Our Clients Say About Us
Types of Auto Insurance
Insurance For Car Collectors By Car Collectors
Our team specializes in providing tailored insurance coverage for car collectors. Whether you own a rare classic, an exotic beauty, or a powerful muscle car, we understand the unique needs of your collection and work to ensure it’s protected with the care and expertise it deserves.



Contact us for better help and services. Explore all types of car insurance
FREQUENTLY ASKED QUESTIONS
At The Phoenix Insurance, we’re committed to answering your most pressing questions to ensure you feel confident about your coverage. From understanding the benefits of working with an independent agency to the specific insurance options we offer for Texas residents, we’ve got you covered.
What makes The Phoenix Insurance different from other insurance providers?
The Phoenix Insurance is an independent agency, meaning we work with multiple insurance carriers to find the best coverage and rates for your unique needs. Our proactive support and commitment to personalized service set us apart from other providers.
Why should I choose an independent insurance agency in Texas?
Independent agencies like The Phoenix Insurance offer more flexibility and personalized service than large, single-carrier companies. We compare coverage options from top-rated carriers to ensure you get the most value for your money.
Does The Phoenix Insurance provide coverage for real estate investors?
Yes, we specialize in insuring real estate investments, including single-family homes, apartments, commercial buildings, and industrial properties. Our team has extensive experience protecting real estate assets across Texas.
How does The Phoenix Insurance handle claims?
We guide clients through the entire claims process, working directly with the insurance carrier to ensure quick and fair resolutions. Our team is dedicated to providing the support you need when it matters most.
What types of insurance does The Phoenix Insurance offer for Texas residents?
We offer a wide range of personal and business insurance options, including home, auto, umbrella, and recreational vehicle coverage for individuals, as well as liability and property insurance for businesses and real estate investors.
Insurance Knowledge. Stories. Tips.
Our Latest Blogs
Explore expert tips, industry insights, and helpful resources from The Phoenix Insurance to stay informed and make confident decisions about your coverage.


Contact Us