
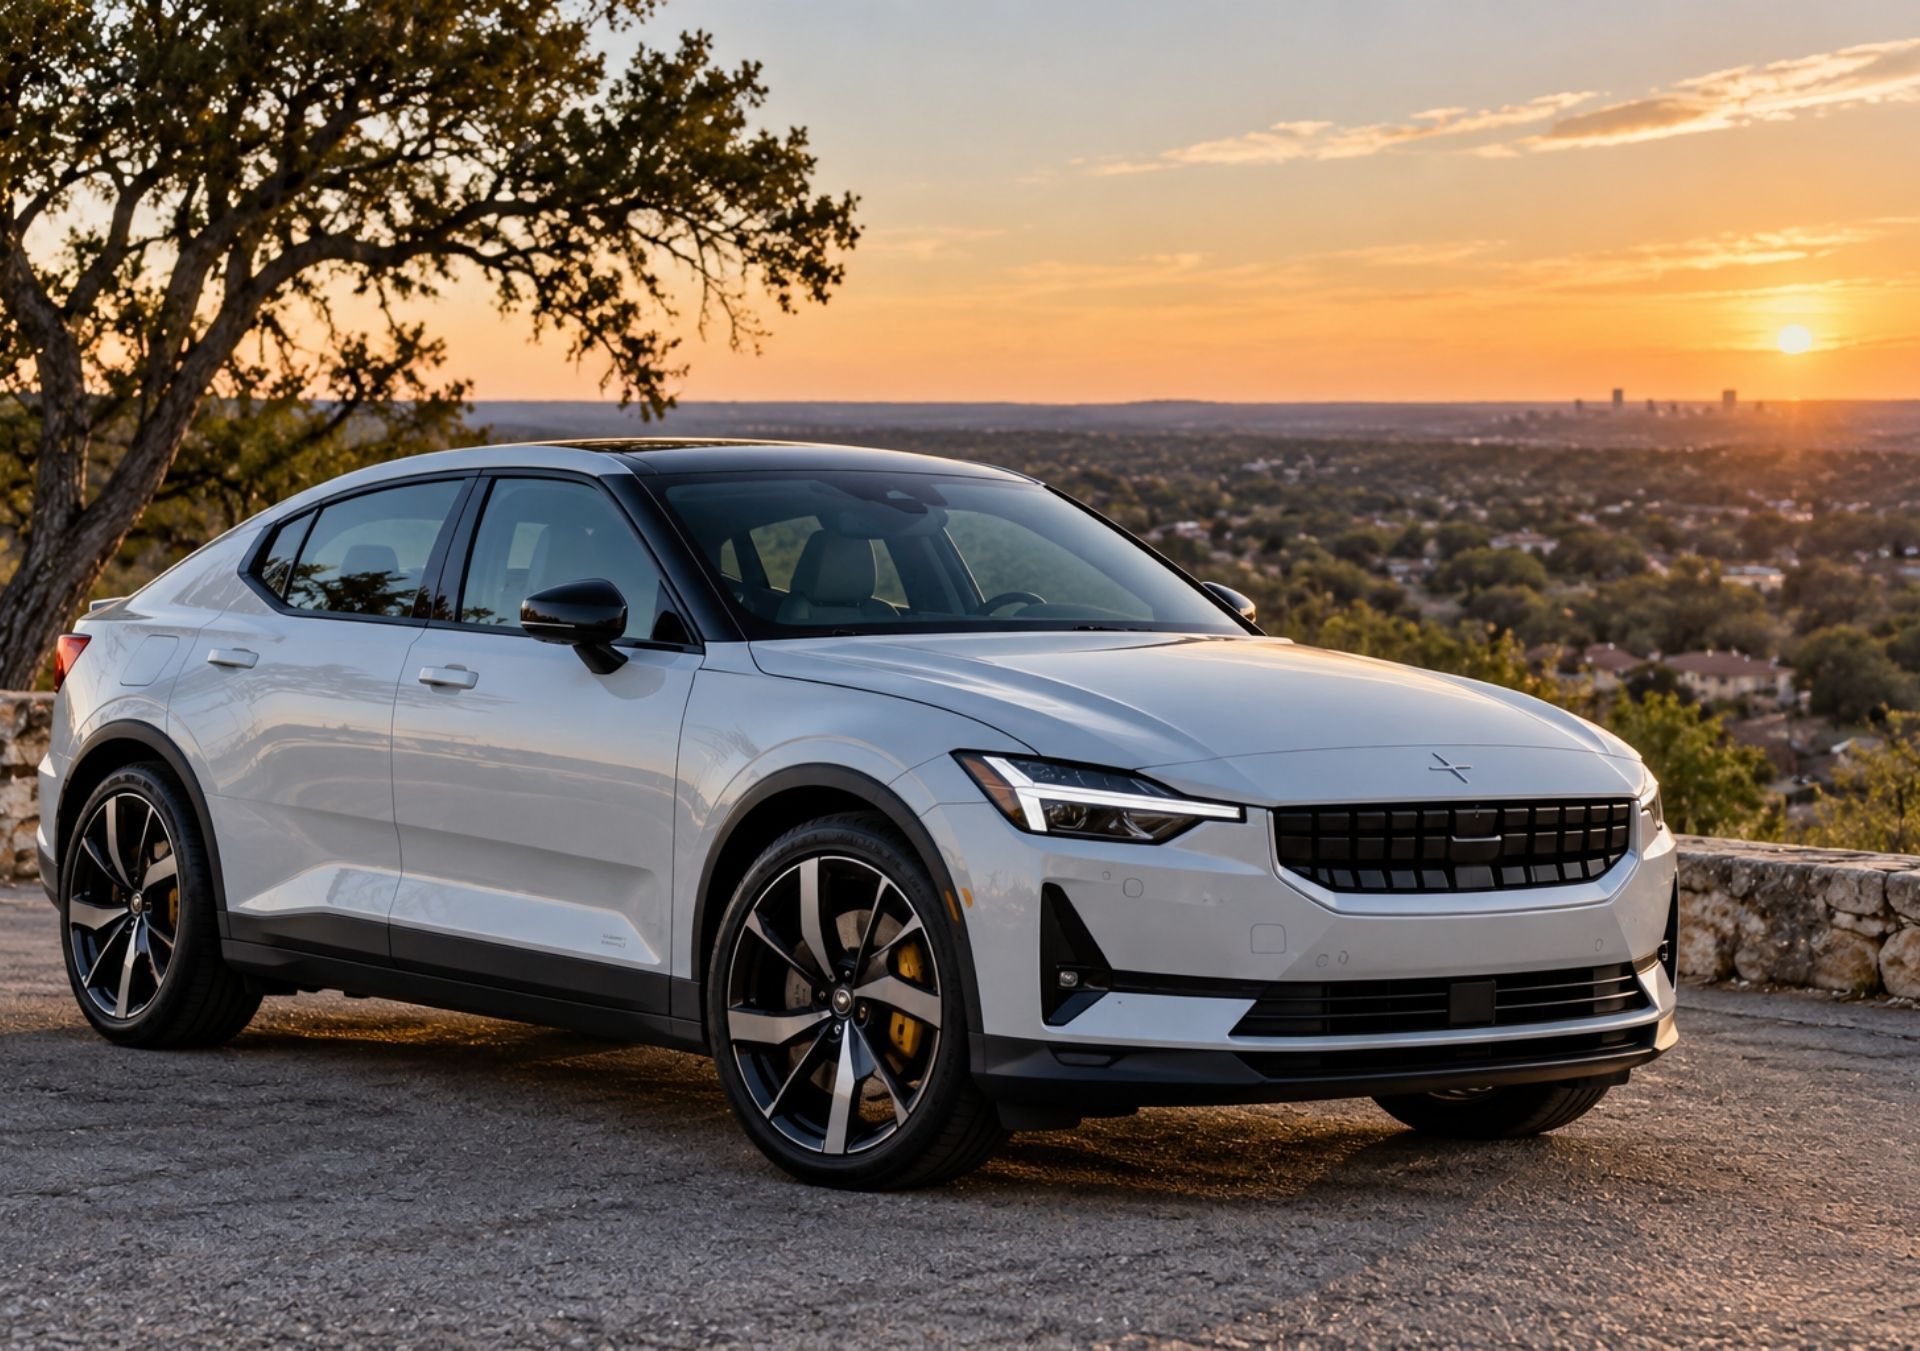
Your Polestar 2 or Polestar 3 isn't a typical sedan sitting in a Texas driveway. It's a premium electric vehicle with specialized components, a battery pack worth thousands, and a market value that can shift quickly. Standard auto insurance policies weren't designed with these realities in mind, and that mismatch can cost you real money after a total loss or major claim. If you're looking for Polestar
insurance in Texas that includes agreed value protection, repair choice, transport coverage, and storage safeguards, you need to understand exactly how these policies work and where generic coverage falls short. The difference between a standard payout and an agreed value settlement on a totaled Polestar 3 can easily reach $10,000 or more, depending on market conditions and your vehicle's configuration. Texas has its own insurance regulations, weather risks, and EV ownership patterns that shape how these policies are structured. Getting this right means fewer surprises and a faster path to fair compensation if something goes wrong.
Understanding Polestar Insurance in Texas
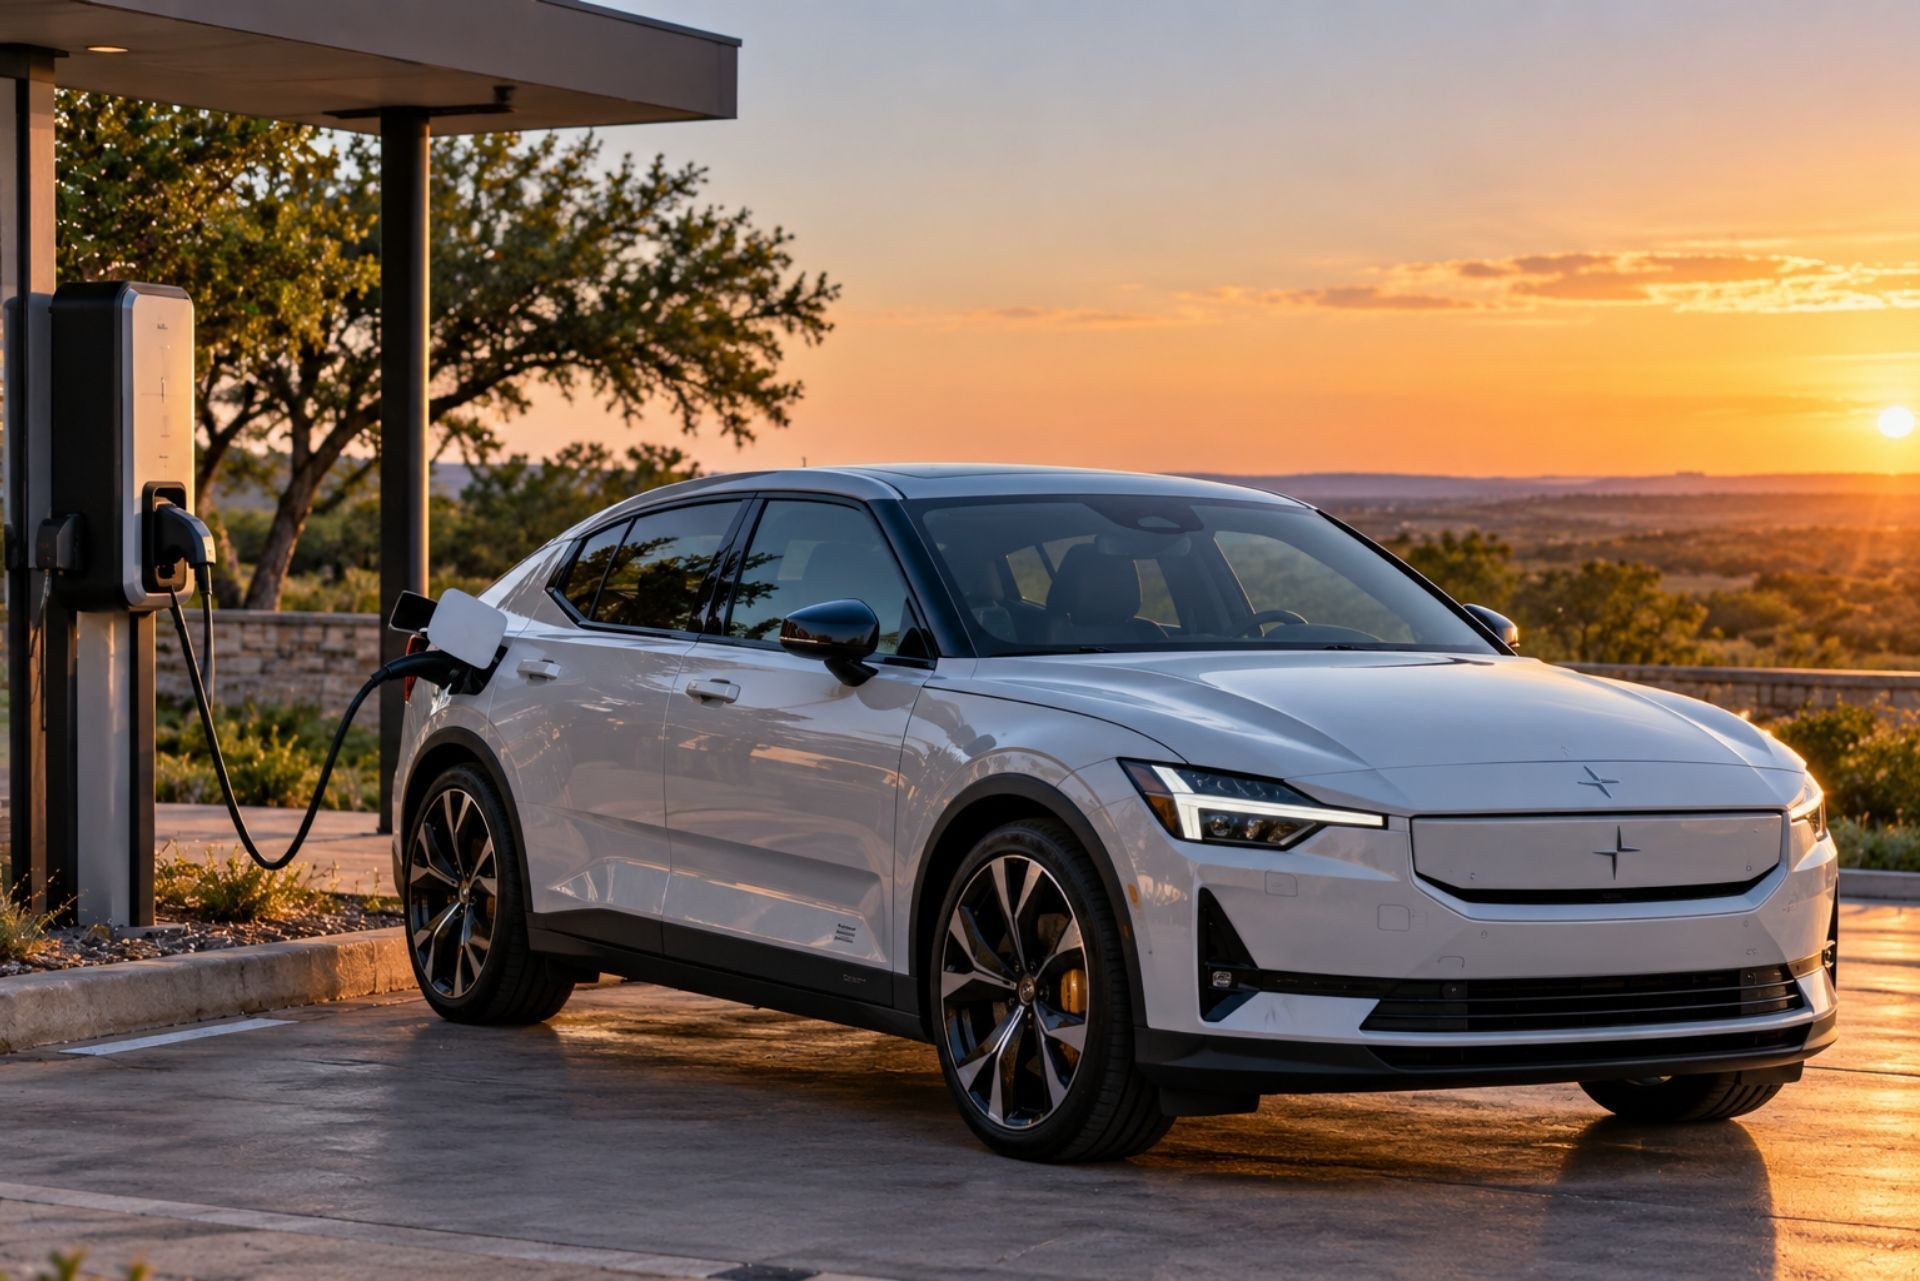
Texas is one of the largest EV markets in the country, and Polestar ownership here comes with a specific set of insurance considerations. Between hailstorms in North Texas, flash flooding along the Gulf Coast, and the sheer number of miles Texans drive, your Polestar faces risks that differ from those in other states. A policy built for a conventional gasoline car often doesn't account for the cost of EV-specific repairs, battery replacement, or the limited number of certified Polestar repair facilities across the state.
Why Texas EV Owners Need Specialized Policies
Most standard auto policies treat your Polestar like any other vehicle in its price bracket. That's a problem. EV repair costs tend to run higher because of specialized parts, high-voltage battery systems, and the need for technicians trained in electric drivetrains. If your insurer sends your car to a body shop that doesn't know how to handle a Polestar's aluminum structure or recalibrate its sensors, you could end up with subpar repairs or even safety issues. A specialized policy gives you the right to choose a certified repair facility, which matters more than most owners realize until they're filing a claim.
The Impact of Rapid EV Depreciation
Electric vehicles, including Polestars, can depreciate faster than their gasoline counterparts in the first few years. New model releases, software updates, and shifting battery technology all push used EV values down. If your Polestar is totaled and your insurer pays
actual cash value, you'll receive whatever the car is worth on the open market at that moment, not what you paid or what it costs to replace. This
depreciation gap is exactly why agreed value coverage exists: it locks in a payout amount upfront, so you're not left absorbing thousands in lost value.
Agreed Value vs. Stated Value Coverage
These two terms sound similar but work very differently in a claim. Confusing them is one of the most common mistakes Polestar owners make when shopping for insurance in Texas.
How Agreed Value Protects Your Investment
With an agreed value policy, you and your insurer negotiate a specific dollar amount for your vehicle before the policy begins. If your Polestar is totaled or stolen, you receive that full agreed amount, minus your deductible. There's no depreciation calculation, no market analysis at the time of loss, and no haggling with an adjuster. You get what you agreed to, period. This is especially valuable for higher-trim Polestar 3 models with performance packs or other factory options that standard valuation tools tend to undercount.
Stated value, on the other hand, sets a ceiling but doesn't guarantee a payout at that level. Your insurer can still apply depreciation or market adjustments, meaning you might receive less than the stated figure. It's a cap, not a promise.
Comparison: Agreed Value vs. Actual Cash Value
The practical difference shows up most clearly after a total loss. Say your Polestar 3 was worth $75,000 when you bought it. Two years later, actual cash value might put it at $55,000 or less. An agreed value policy set at $70,000 would pay $70,000 minus your deductible. An actual cash value policy would pay whatever the market says the car is worth that week, which could be significantly lower. For a vehicle with
full-coverage insurance averaging around $3,500 annually in Texas, the premium difference for agreed value protection is often modest relative to the payout gap.
Standard vs. Agreed Value Policy Comparison
Seeing the differences side by side makes the choice clearer. Here's how a standard policy stacks up against one built around agreed value, repair choice, and transport and storage protections for your Polestar.
Comparison Chart: Valuation and Payouts
| Feature | Standard Policy | Agreed Value Policy |
|---|---|---|
| Total Loss Payout | Actual cash value at time of loss | Pre-agreed amount, no depreciation applied |
| Repair Facility | Insurer-selected shop | Owner chooses certified Polestar facility |
| Transport Coverage | Limited or excluded | Covered during transit to shows, service, etc. |
| Storage Protection | Homeowner's policy may partially cover | Dedicated coverage for stored vehicles |
| Depreciation Impact | Reduces payout over time | Locked in, regardless of market shifts |
| Premium Cost | Lower baseline | Moderately higher, varies by agreed amount |
| Appraisal Required | No | Yes, typically at policy inception |
The catch is that agreed value policies require more effort upfront. You'll need documentation, an appraisal, and sometimes photos of your vehicle's condition. But that paperwork protects you from the kind of lowball settlement that leaves owners frustrated after a loss.
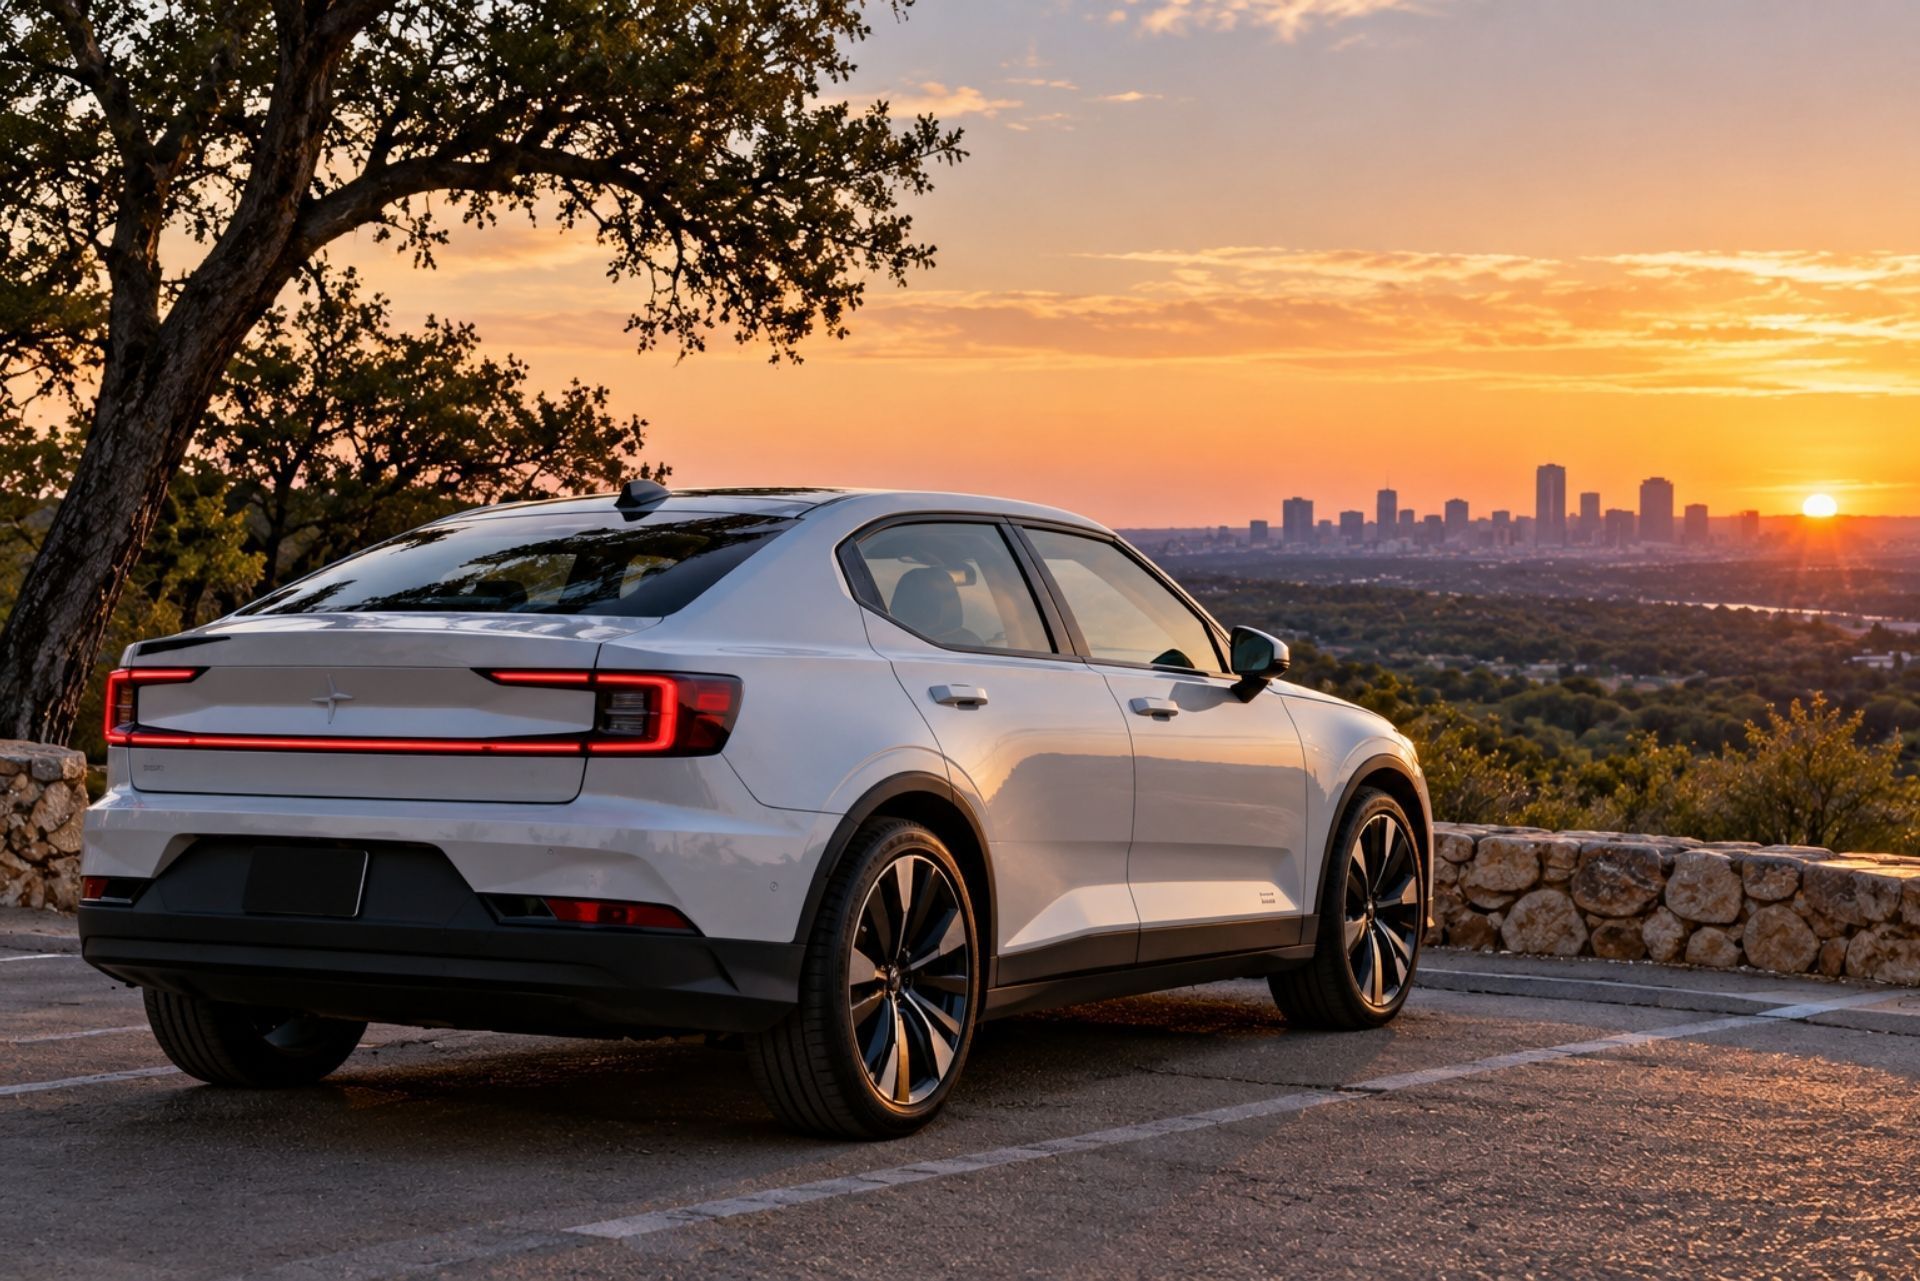
Not every Polestar automatically qualifies for agreed value coverage. Insurers have specific requirements, and Texas regulations add another layer to the process.
Required Documentation and Appraisals
To secure an agreed value policy, you'll typically need a professional appraisal from a qualified appraiser who understands EV valuations. This isn't the same as a Kelley Blue Book estimate. The appraisal should document your Polestar's exact configuration, mileage, condition, and any factory or dealer-installed options. High-resolution photos of the exterior, interior, and odometer reading are standard requirements.
Keep a digital inventory of all documentation, including your original purchase agreement, window sticker, and records of any modifications. Many insurers also want maintenance records showing the vehicle has been properly serviced. Plan to update your appraisal every two to three years, or sooner if market values shift significantly. This keeps your agreed amount aligned with reality and prevents disputes at claim time.
Policy Limits and Premium Factors
Your premium for agreed value coverage depends on several factors: the agreed amount itself, your driving history, where in Texas you garage the vehicle, and your chosen deductible. A Polestar 3 with a 1.00x actuarial multiplier in Texas means insurers view its risk profile as average for the state, which helps keep premiums reasonable. That said, choosing a higher agreed value naturally increases your premium.
Texas weather plays a role too. If you're in a hail-prone area like the Dallas-Fort Worth metroplex, your comprehensive coverage costs will reflect that risk. Owners who store their Polestar in a climate-controlled garage and drive fewer annual miles often qualify for discounts. One thing to keep in mind: Texas House Bill 2067, effective in 2026, now
requires insurers to provide written explanations for any policy cancellation or non-renewal, giving you more transparency if your coverage is ever dropped.
Frequently Asked Questions About Polestar Insurance
What happens if my Polestar is totaled in Texas?
With an agreed value policy, you receive the pre-negotiated amount minus your deductible. With a standard actual cash value policy, the insurer determines your car's market value at the time of the loss, which can be thousands less than what you paid. File your claim promptly and have your documentation ready to speed up the process, keeping in mind that under the Texas Prompt Payment of Claims Act, insurers have 15 business days to acknowledge receipt of a claim and begin an investigation. https://santexpublicadjusters.com/how-long-does-an-insurance-company-have-to-pay-a-property-claim-in-texas-deadlines-delays-and-what-to-do-next/
Does agreed value coverage cost more than standard insurance?
Yes, but the difference is often smaller than owners expect. For many Polestar models, the annual premium increase ranges from a few hundred dollars, depending on your agreed amount and other rating factors. The real question is whether that extra cost is worth the protection against a depreciation-driven payout shortfall.
Can I get this coverage for a leased Polestar?
Typically, no. Agreed value coverage is designed for vehicle owners, not lessees. If you're leasing, your lienholder usually dictates the insurance requirements, and gap insurance is more commonly paired with leases to cover the difference between the car's value and your remaining lease balance.
Do I need a new appraisal every year?
Most insurers don't require annual appraisals, but updating every two to three years is a smart practice. If your Polestar's market value has changed significantly, whether up or down, an updated appraisal ensures your agreed amount stays accurate. Some insurers will adjust the agreed value at renewal based on market data without a full reappraisal.
Is this the same thing as Gap insurance?
No. Gap insurance covers the difference between your car's actual cash value and what you still owe on a loan or lease. Agreed value coverage replaces the actual cash value calculation entirely with a fixed payout amount. If you own your Polestar outright and it's fully paid off, gap insurance is irrelevant, but agreed value coverage still protects you from depreciation losses.
Making the Right Choice for Your EV
Insuring a Polestar in Texas isn't just about meeting the state's minimum liability requirements. It's about protecting a significant investment from the specific risks that EV owners face: rapid depreciation, expensive repairs, limited certified service networks, and the unpredictable Texas climate. Agreed value coverage removes the guesswork from a total loss claim, while repair choice provisions ensure your car is fixed correctly by technicians who know the vehicle. Transport and storage coverage fills the gaps that standard policies ignore entirely.
Start by getting a professional appraisal of your Polestar's current value and condition. Gather your purchase documents, maintenance records, and photos. Then talk to an insurer or broker who specializes in EV or specialty vehicle coverage, not just a general auto policy provider. Ask specifically about agreed value options, certified repair networks in your area, and whether transport and storage are included or available as endorsements. The time you invest now pays off the moment you need to file a claim, and in Texas, that moment can come faster than you'd expect.
About The Author: Aaron Husman
As COO of The Phoenix Insurance, I’m focused on building lasting client relationships and delivering insurance solutions that make protection simple and effective. With years of experience in commercial and personal insurance, I take pride in helping individuals and businesses find coverage that brings confidence and peace of mind.
customer reviews
See What Our Clients Say About Us
Types of Auto Insurance
Insurance For Car Collectors By Car Collectors
Our team specializes in providing tailored insurance coverage for car collectors. Whether you own a rare classic, an exotic beauty, or a powerful muscle car, we understand the unique needs of your collection and work to ensure it’s protected with the care and expertise it deserves.



Contact us for better help and services. Explore all types of car insurance
FREQUENTLY ASKED QUESTIONS
At The Phoenix Insurance, we’re committed to answering your most pressing questions to ensure you feel confident about your coverage. From understanding the benefits of working with an independent agency to the specific insurance options we offer for Texas residents, we’ve got you covered.
What makes The Phoenix Insurance different from other insurance providers?
The Phoenix Insurance is an independent agency, meaning we work with multiple insurance carriers to find the best coverage and rates for your unique needs. Our proactive support and commitment to personalized service set us apart from other providers.
Why should I choose an independent insurance agency in Texas?
Independent agencies like The Phoenix Insurance offer more flexibility and personalized service than large, single-carrier companies. We compare coverage options from top-rated carriers to ensure you get the most value for your money.
Does The Phoenix Insurance provide coverage for real estate investors?
Yes, we specialize in insuring real estate investments, including single-family homes, apartments, commercial buildings, and industrial properties. Our team has extensive experience protecting real estate assets across Texas.
How does The Phoenix Insurance handle claims?
We guide clients through the entire claims process, working directly with the insurance carrier to ensure quick and fair resolutions. Our team is dedicated to providing the support you need when it matters most.
What types of insurance does The Phoenix Insurance offer for Texas residents?
We offer a wide range of personal and business insurance options, including home, auto, umbrella, and recreational vehicle coverage for individuals, as well as liability and property insurance for businesses and real estate investors.
Insurance Knowledge. Stories. Tips.
Our Latest Blogs
Explore expert tips, industry insights, and helpful resources from The Phoenix Insurance to stay informed and make confident decisions about your coverage.


Contact Us