
A Saleen isn't just another Mustang with a body kit. Whether you own a numbers-matching S281, a rare S351, or one of the handful of S7 supercars still in private hands, your vehicle sits in a category that most insurance carriers simply don't understand. The modifications, limited production runs, and collector demand mean your Saleen's real-world value can be two, three, or even ten times what a standard policy would pay after a total loss. That gap between what your car is worth and what a generic insurer would cut you a check for is the single biggest financial risk most Saleen owners overlook.
Texas adds its own layer of complexity. Hailstorms roll through San Antonio and Dallas with regularity, summer heat punishes paint and interiors, and the state's sheer size means any trip to a show or specialty shop involves serious mileage. Getting the right insurance for your Saleen in Texas means locking down agreed value coverage, protecting your right to choose who touches the car, and making sure transport and storage are part of the equation. This guide breaks down each of those pillars so you can make informed decisions before a claim forces your hand.
Protecting Your Saleen Investment in Texas
Owning a Saleen in Texas means contending with weather extremes, long highway stretches, and a limited pool of qualified technicians. A standard auto policy treats your car like any other vehicle on the road, and that's where the trouble starts. The financial exposure you face after a loss event, whether it's a hailstorm in Fort Worth or a rear-end collision on I-35, depends entirely on the type of policy sitting in your glovebox.
Why Standard Auto Policies Fall Short for Saleen Owners
A typical personal auto policy uses Actual Cash Value, or ACV, to determine what you're owed after a total loss. ACV takes the original price, subtracts depreciation, and spits out a number based on comparable sales of similar vehicles. The problem? There are no truly comparable sales for a low-production Saleen. Your insurer's algorithm might pull comps from base-model Mustangs or generic "modified Ford" listings, leaving you tens of thousands of dollars short.
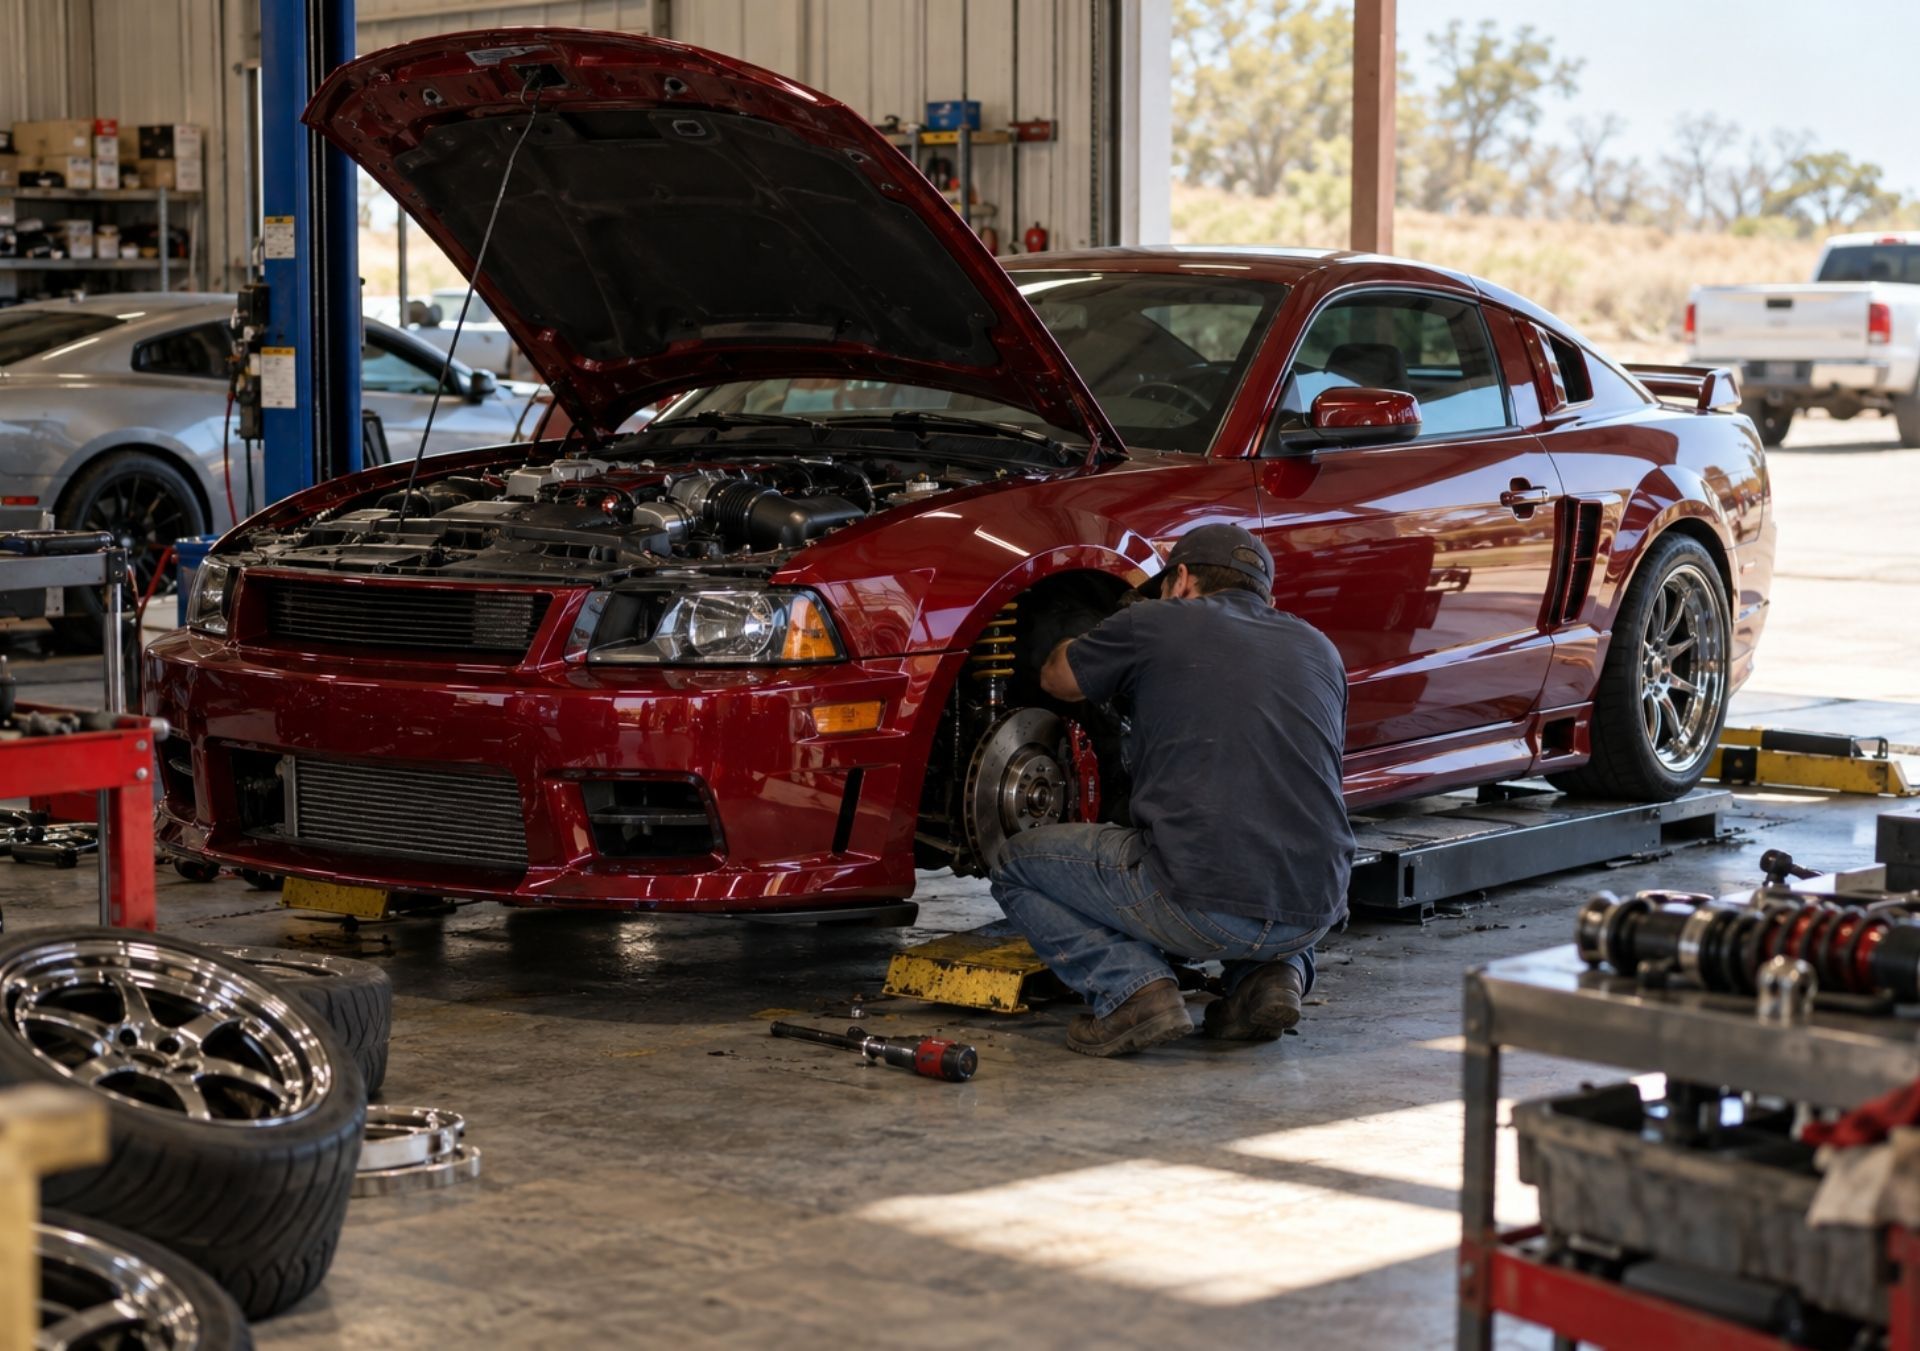
Standard policies also restrict where you can have repairs done. Most carriers steer you toward their network of preferred shops, which are volume-focused body shops that have never seen a Saleen supercharger, let alone know how to source Saleen-specific panels. You also won't find transport or storage riders on a conventional policy, so moving your car to a show or storing it over winter in a climate-controlled facility creates coverage gaps.
The Difference Between Market Value and Agreed Value
Market value is whatever the insurer's database says your car is worth on the day of the loss. Agreed value is a number you and the insurer negotiate before the policy starts, backed by a professional appraisal and documentation. With an agreed value policy, there's no depreciation calculation and no argument about comps. If your S281 is insured for an agreed amount and it's totaled, you get that full amount, minus your deductible. https://www.progressive.com/answers/agreed-value-insurance/
This matters because Saleen values have been climbing. The S7, in particular, has seen auction results that would have seemed absurd a decade ago. Even well-documented S281s and S351s from the early 2000s are appreciating as the collector market recognizes their significance. An ACV policy can't keep up with that trajectory. An agreed value policy locks in your car's worth today and can be updated as the market moves.
Securing an Agreed Value Policy
Getting an agreed value policy isn't as simple as calling your current carrier and asking for one. Most mainstream insurers don't offer true agreed value for collector or modified vehicles. You'll need to work with a specialty carrier, and you'll need to come prepared.
How Appraisals and Documentation Protect Your Equity
A professional appraisal is the foundation of any agreed value policy. Hire an appraiser who understands Saleen production history, option codes, and the difference between a Saleen-modified vehicle and an aftermarket clone. The appraisal should include detailed photographs, a condition report, verification of the Saleen VIN plate or CSM number, and recent comparable sales from Bring a Trailer, Mecum, or private transactions.
Keep your documentation current. Specialty insurers typically recommend updating appraisals every two to three years, or sooner if the market shifts significantly. Digital inventory tools make this easier: photograph every angle of the car, save receipts for maintenance and upgrades, and store everything in the cloud so it's accessible after a loss. Texas Senate Bill 458, effective January 1, 2026, established a new appraisal framework for personal auto insurance disputes, giving Saleen owners a formal process to challenge an insurer's valuation if a disagreement arises.
Comparing Policy Types for Performance Vehicles
Not all specialty policies are created equal. Some carriers offer "stated value" policies that look like agreed value but include fine print allowing the insurer to pay the lesser of the stated amount or actual cash value. That's not the same thing. True agreed value means the declared amount is the payout, period.
When shopping for coverage, ask these specific questions: Does the policy guarantee the agreed amount with no depreciation? Are there mileage restrictions, and do they fit your driving habits? Does the policy include coverage for transport to shows and events? What about storage in a facility that isn't your primary garage? The answers will separate genuine collector-car insurers from companies that bolt a rider onto a standard policy and call it specialty coverage.
Comparison: Standard vs. Specialty Saleen Coverage
A side-by-side look makes the differences impossible to ignore. Here's how a standard Texas auto policy stacks up against a specialty policy built for vehicles like your Saleen:
| Coverage Feature | Standard Auto Policy | Specialty Saleen Policy |
|---|---|---|
| Valuation Method | Actual Cash Value (depreciated) | Agreed Value (pre-negotiated) |
| Repair Shop Choice | Insurer's preferred network | Owner's choice, including Saleen-certified shops |
| OEM Parts Guarantee | Not guaranteed; aftermarket substitutes common | OEM and Saleen-specific parts required |
| Transport Coverage | Typically excluded | Included or available as rider |
| Storage Coverage | Limited to listed garage | Extends to off-site climate-controlled facilities |
| Mileage Limits | None | Often 1,000-7,500 miles/year |
| Show/Event Coverage | Not addressed | Transit and show riders available |
| Appraisal Dispute Process | Standard claims process | Formal appraisal framework (TX SB 458) |
The catch is that specialty policies often carry mileage caps. If your Saleen is a daily driver, you may need a hybrid approach: a standard policy for liability and a specialty overlay for physical damage. Most Saleen owners, though, keep mileage low enough that a pure collector policy works well.
Guaranteeing Your Right to Repair Choice
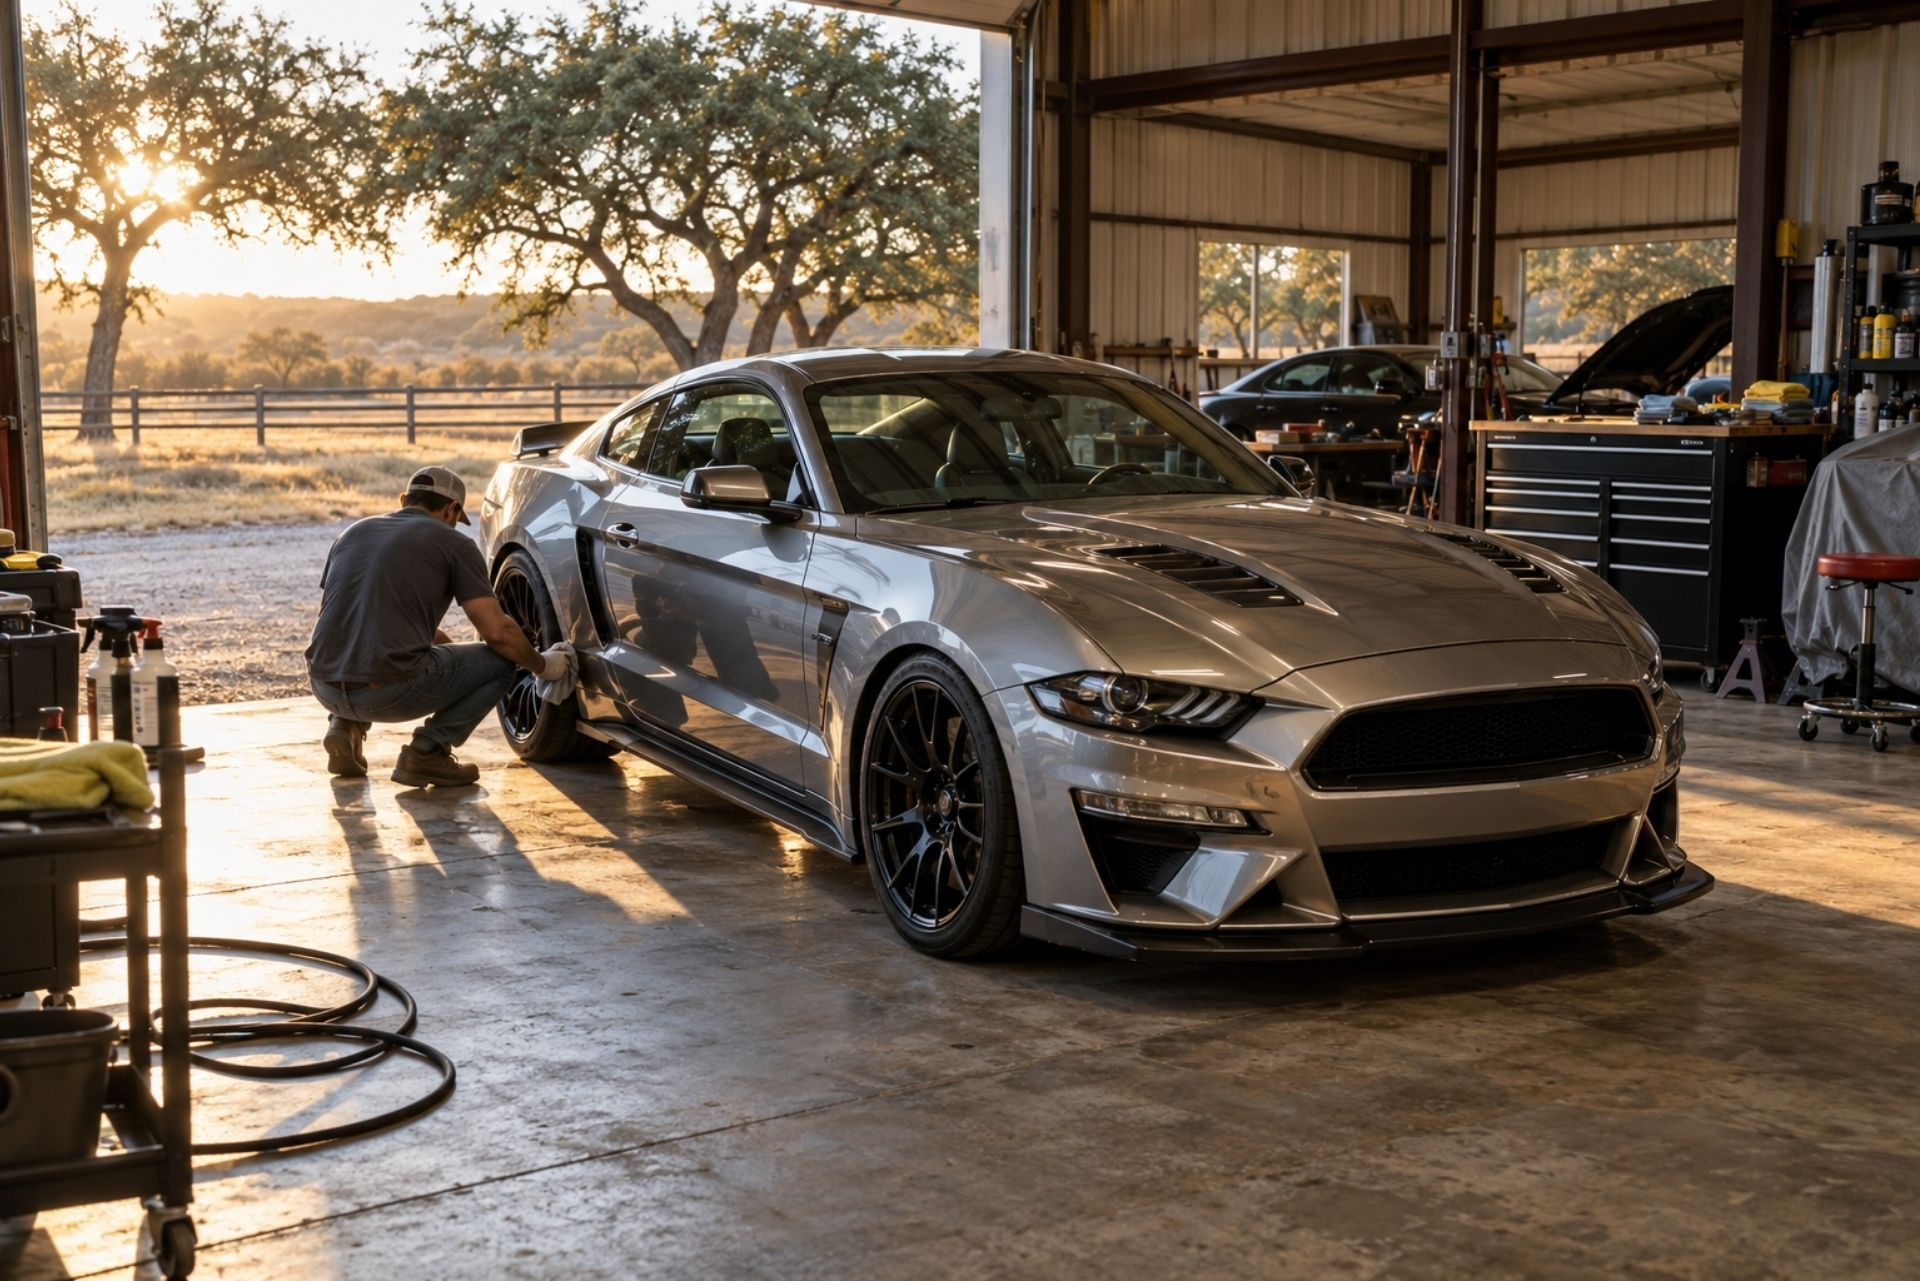
After a covered loss, who fixes your car matters as much as what you're paid. A botched repair on a Saleen can destroy provenance, reduce resale value, and compromise performance. Texas law gives you the right to choose your own repair facility, but exercising that right takes some knowledge.
The Importance of Using Saleen-Certified Technicians
Saleen vehicles use proprietary supercharger systems, suspension geometry, and body components that differ from their Ford counterparts. A general body shop might be able to straighten a fender, but aligning a Saleen-specific front fascia or recalibrating a Watts-link rear suspension requires specialized training. Using an unqualified shop risks voiding any remaining Saleen warranty coverage and can introduce problems that surface months later.
Texas HB 2963, effective September 1, 2026, strengthens the right to repair by requiring manufacturers to provide documentation and tools to third-party technicians. This is good news for Saleen owners who rely on independent specialists rather than a factory service center. That said, "access to documentation" doesn't replace hands-on experience. Vet your shop carefully, ask for references from other Saleen owners, and confirm they've worked on your specific model before authorizing any repairs.
Understanding OEM Parts Coverage in Texas
One of the most common fights between owners and insurers involves parts. A standard policy may authorize aftermarket fenders, generic brake components, or non-Saleen exhaust pieces. On a collector vehicle, aftermarket parts can slash value and compromise the car's authenticity.
Your specialty policy should explicitly require OEM and Saleen-specific parts for all covered repairs. Get this in writing before you need it. If a part is discontinued or on backorder, the policy should cover the cost of sourcing it from a Saleen parts vendor or fabricating a correct replacement. Don't assume your insurer understands the difference between a stock Ford Mustang hood and a Saleen-specific piece. Spell it out in the policy documents, and keep a parts reference sheet with your appraisal file.
Common Questions About Texas Saleen Insurance
Do I need a separate policy for my Saleen, or can I add it to my regular auto insurance? Most standard carriers can't provide true agreed value or repair choice guarantees. A standalone specialty policy from a collector-car insurer is almost always the better option for protecting your Saleen's full value.
How often should I update my Saleen's appraisal? Every two to three years is a solid baseline. If auction results for your model spike or you complete a significant restoration, get a new appraisal sooner so your agreed value reflects current reality.
Will my Saleen be covered if I trailer it to a car show? Only if your policy includes a transport or "transit and show" rider. The Saleen Club of America's "Saleen Invade San Antonio" event in November 2026 is exactly the kind of occasion where you'd want this coverage active. Confirm with your insurer before loading up.
Does Texas law let me pick my own repair shop after a claim? Yes. Texas gives you the right to choose your repair facility. Your insurer can recommend shops, but they can't force you into their network. Insist on a shop with Saleen experience.
What happens if my insurer and I disagree on my car's value after a loss? Under the appraisal framework established by Texas SB 458, you can trigger a formal appraisal process. Each side selects an appraiser, and if those two can't agree, an umpire makes the final call.
Is storage in a rented climate-controlled unit covered?
Standard policies typically only cover vehicles at the address listed on your policy. Specialty policies can extend coverage to off-site storage facilities, which is critical if you rent space in a climate-controlled warehouse to protect your Saleen from Texas heat and humidity.
The Bottom Line for Your Saleen
Your Saleen represents a specific slice of American performance history, and protecting it requires insurance that matches its uniqueness. Agreed value coverage eliminates the guesswork after a total loss. Repair choice guarantees keep your car in the hands of qualified technicians using correct parts. Transport and storage riders close the gaps that standard policies ignore entirely.
Texas owners have new tools available in 2026, from the SB 458 appraisal dispute framework to expanded right-to-repair protections under HB 2963. Use them. Get a current appraisal, document every detail of your car digitally, and work with a specialty insurer who understands what makes a Saleen different from the Ford it started as.
Don't wait for a hailstorm in April or a fender bender on the way to San Antonio to find out your policy falls short. Review your coverage now, ask the hard questions, and make sure the policy you're paying for actually protects the car you own.
About The Author: Aaron Husman
As COO of The Phoenix Insurance, I’m focused on building lasting client relationships and delivering insurance solutions that make protection simple and effective. With years of experience in commercial and personal insurance, I take pride in helping individuals and businesses find coverage that brings confidence and peace of mind.
customer reviews
See What Our Clients Say About Us
Types of Auto Insurance
Insurance For Car Collectors By Car Collectors
Our team specializes in providing tailored insurance coverage for car collectors. Whether you own a rare classic, an exotic beauty, or a powerful muscle car, we understand the unique needs of your collection and work to ensure it’s protected with the care and expertise it deserves.



Contact us for better help and services. Explore all types of car insurance
FREQUENTLY ASKED QUESTIONS
At The Phoenix Insurance, we’re committed to answering your most pressing questions to ensure you feel confident about your coverage. From understanding the benefits of working with an independent agency to the specific insurance options we offer for Texas residents, we’ve got you covered.
What makes The Phoenix Insurance different from other insurance providers?
The Phoenix Insurance is an independent agency, meaning we work with multiple insurance carriers to find the best coverage and rates for your unique needs. Our proactive support and commitment to personalized service set us apart from other providers.
Why should I choose an independent insurance agency in Texas?
Independent agencies like The Phoenix Insurance offer more flexibility and personalized service than large, single-carrier companies. We compare coverage options from top-rated carriers to ensure you get the most value for your money.
Does The Phoenix Insurance provide coverage for real estate investors?
Yes, we specialize in insuring real estate investments, including single-family homes, apartments, commercial buildings, and industrial properties. Our team has extensive experience protecting real estate assets across Texas.
How does The Phoenix Insurance handle claims?
We guide clients through the entire claims process, working directly with the insurance carrier to ensure quick and fair resolutions. Our team is dedicated to providing the support you need when it matters most.
What types of insurance does The Phoenix Insurance offer for Texas residents?
We offer a wide range of personal and business insurance options, including home, auto, umbrella, and recreational vehicle coverage for individuals, as well as liability and property insurance for businesses and real estate investors.
Insurance Knowledge. Stories. Tips.
Our Latest Blogs
Explore expert tips, industry insights, and helpful resources from The Phoenix Insurance to stay informed and make confident decisions about your coverage.


Contact Us