
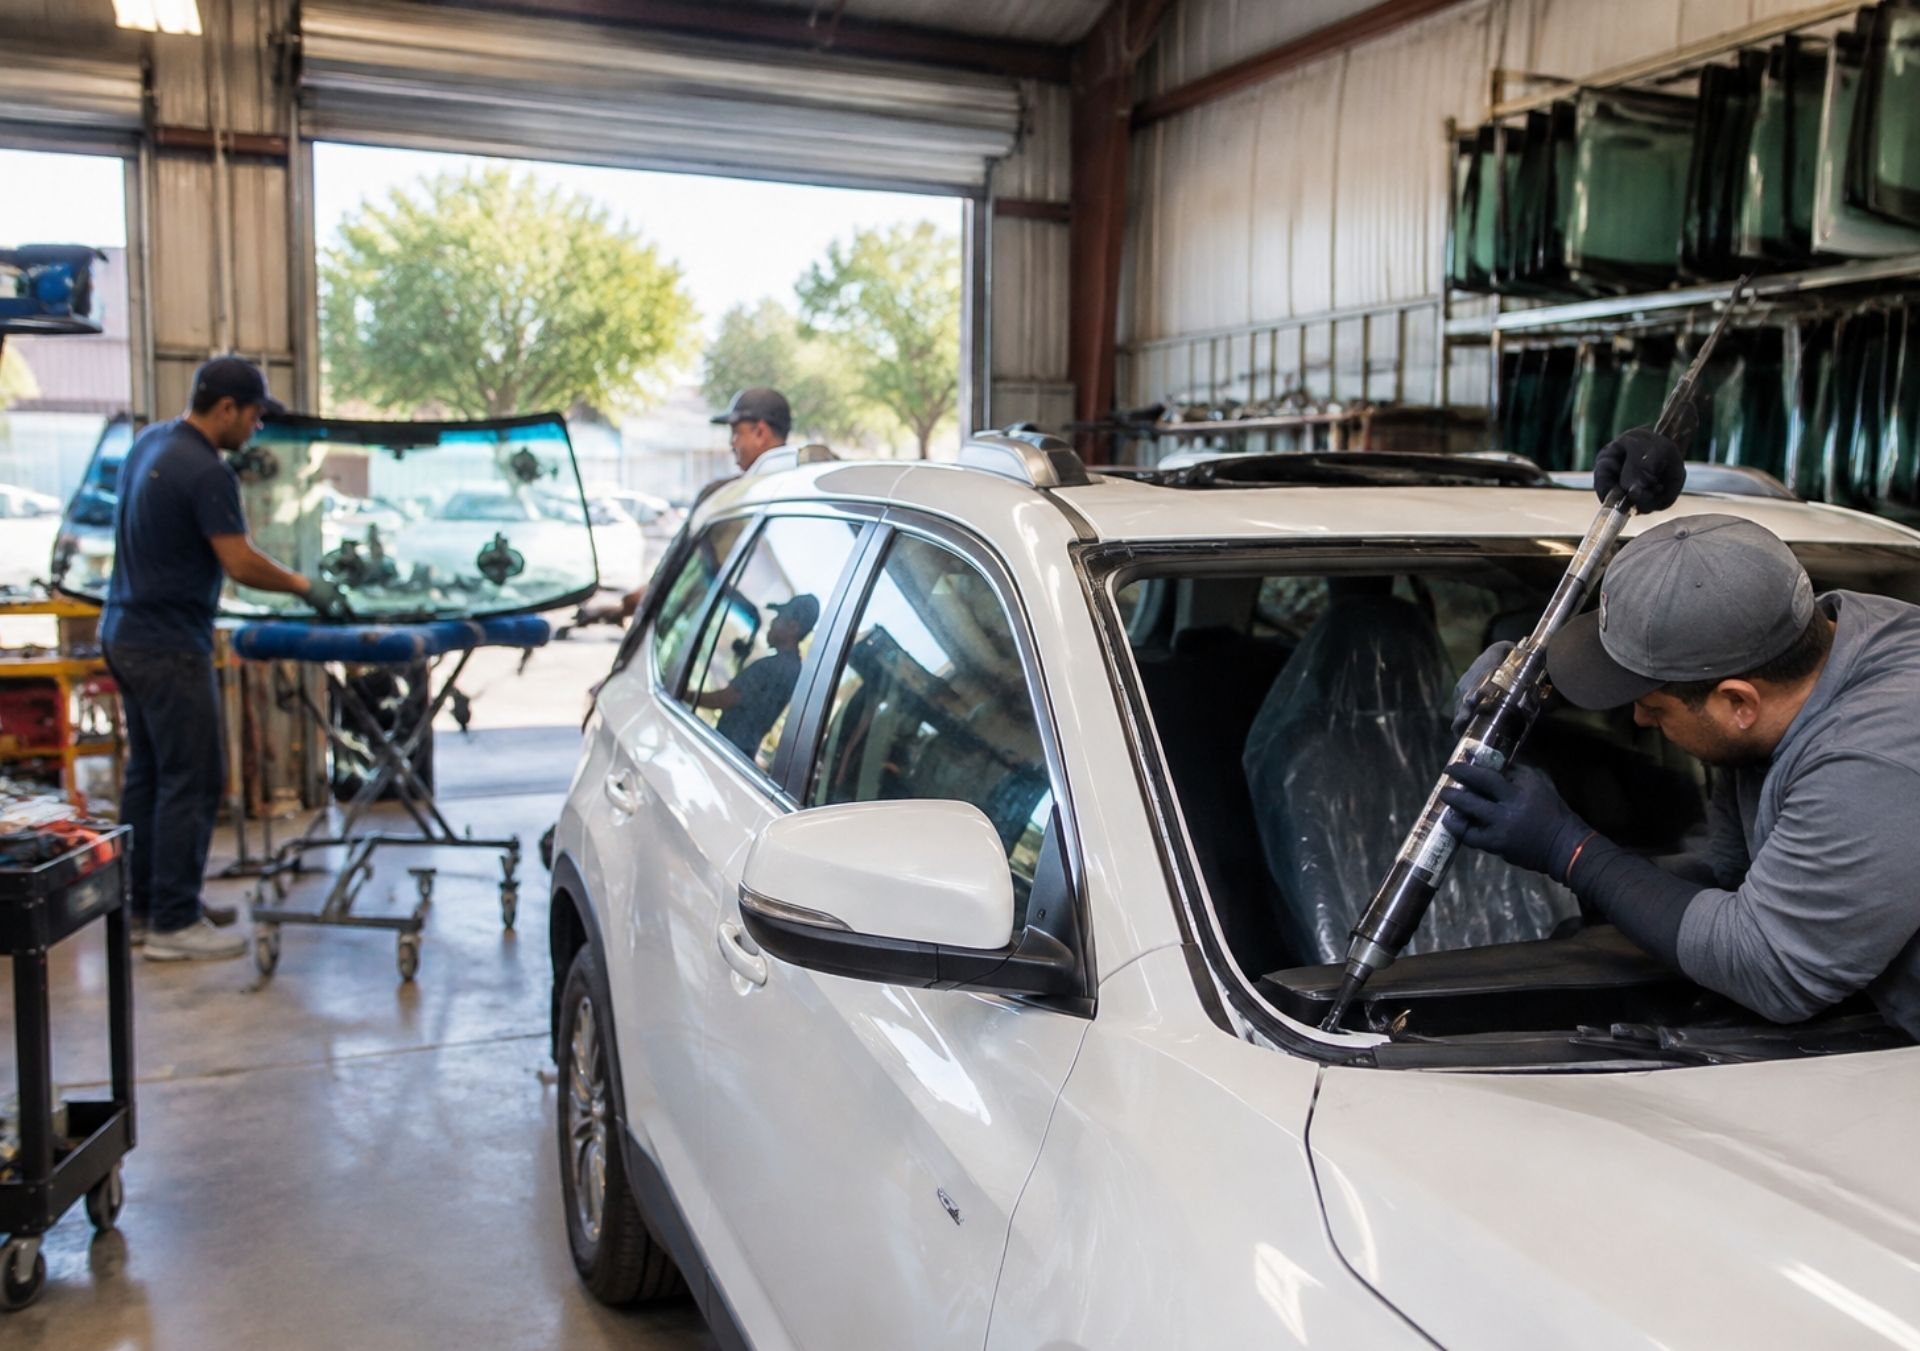
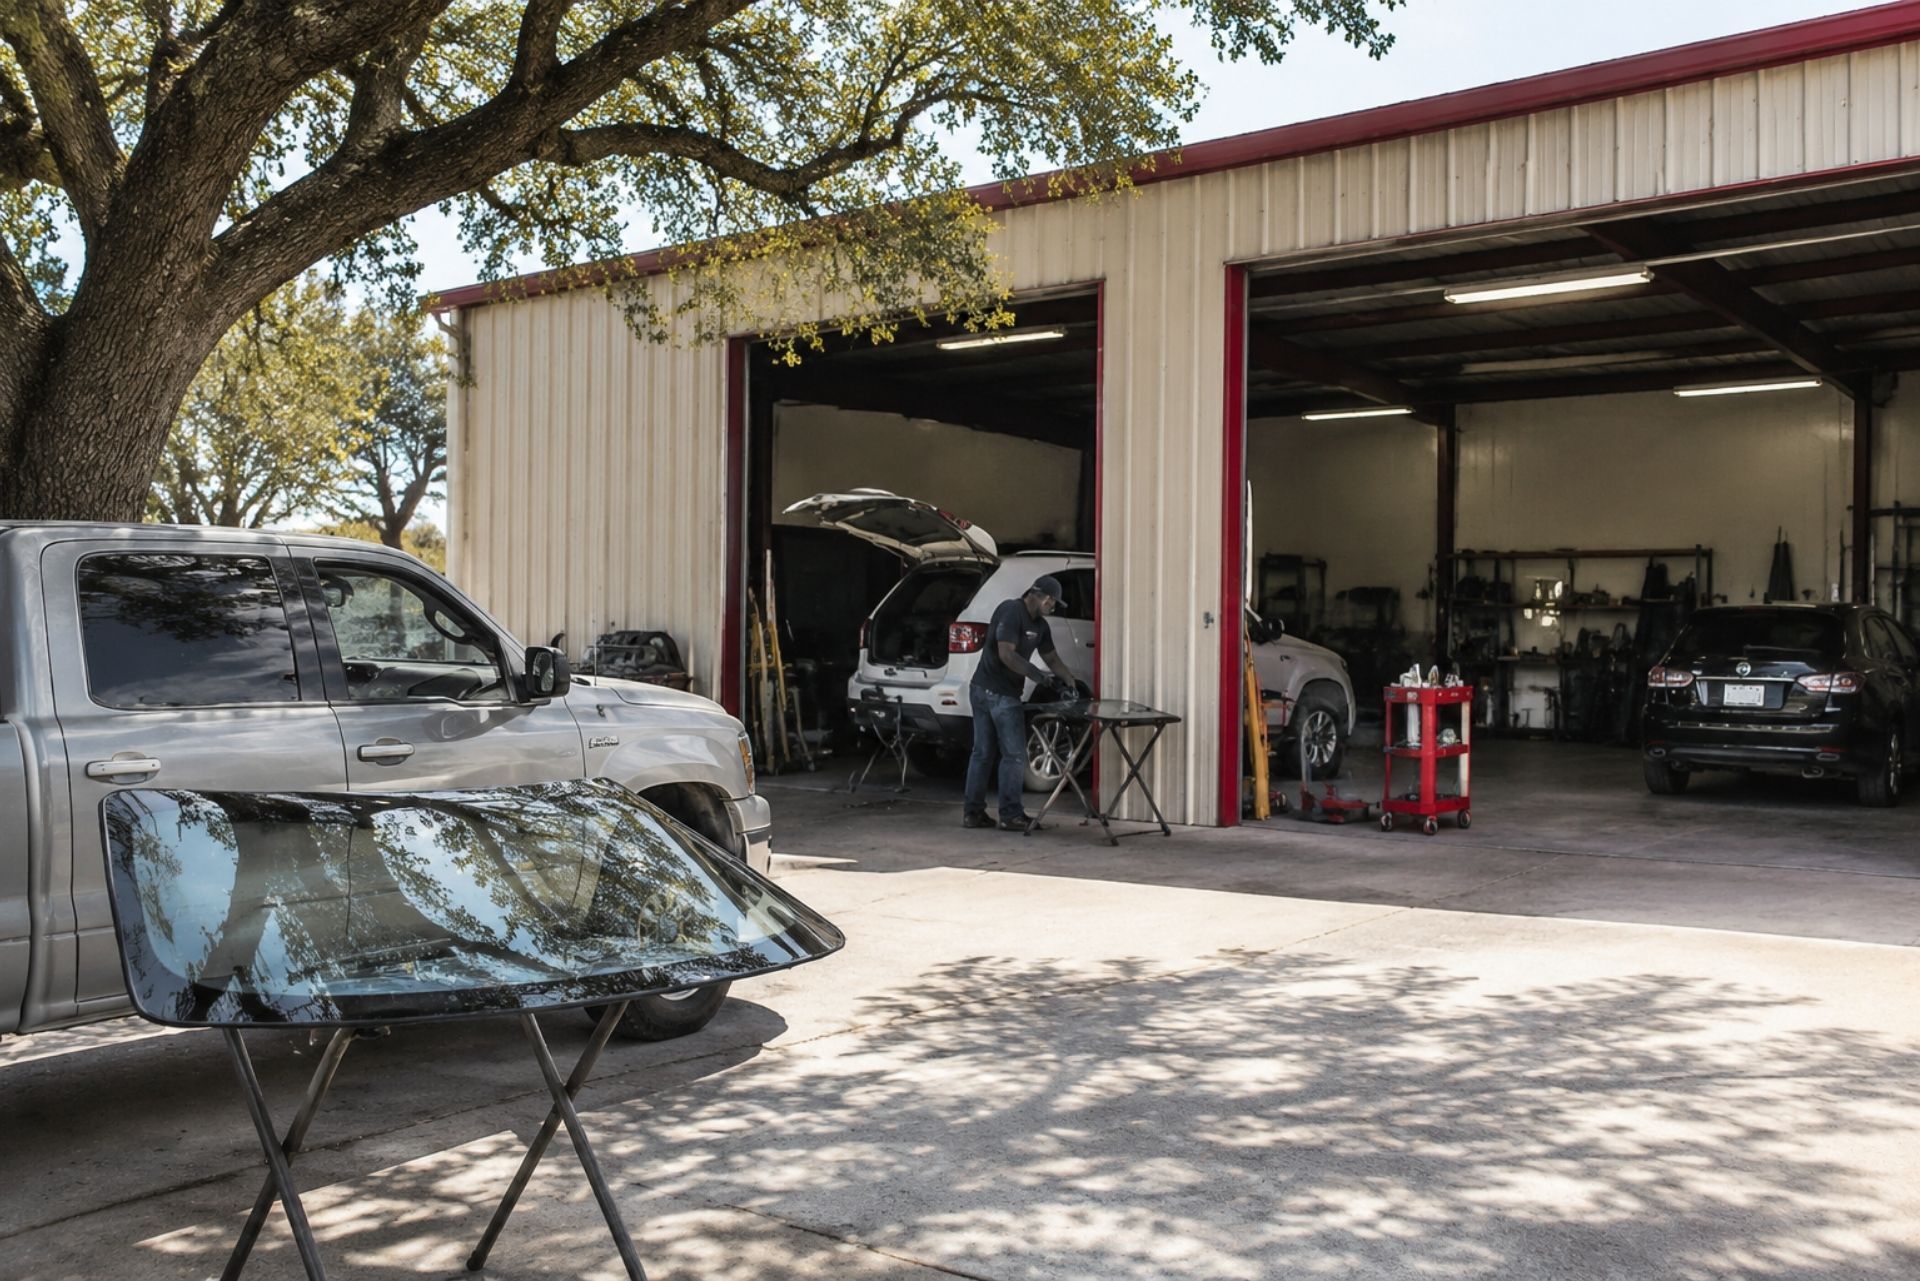
Picture a customer's 2025 Tesla Model Y parked in your bay overnight with a fresh windshield curing. A hailstorm rolls through, your roof leaks, and the car's ADAS camera housing takes water damage. Who pays? For Texas auto glass shops, the answer depends on how you've built your insurance across liability, property, customer vehicles, and lost income. Most owners discover their gaps only after a claim gets denied.
Texas adds its own pressure points. Hail season hits Dallas-Fort Worth hard, Gulf Coast shops face hurricane exposure, and mobile techs log serious miles across Houston and San Antonio. Rates are moving too. Here's how to put together coverage that holds up when something goes wrong.
Essential Liability and Garagekeepers Coverage for Texas Shops
Liability is where most auto glass claims start. A windshield that pops loose on I-35 because the urethane didn't cure properly isn't a property claim. It's a bodily injury lawsuit, and it can follow your shop for years.
Your liability program needs to answer two separate questions. What happens when your work or your premises hurt someone? And what happens when a customer's car gets damaged while you're responsible for it? Those are different exposures, and they're covered by different policies.
For small-to-mid-sized Texas repair shops, garage liability premiums average around $2,800 a year in 2026, with most shops paying between $1,300 and $5,000. Where you land depends on payroll, mobile operations, claims history, and whether you perform ADAS recalibration.
That last factor matters more every year. Standard static recalibration in Texas runs $150 to $400, but luxury and electric vehicles needing both static and dynamic calibration can top $1,000. If a recalibration error causes a lane-keep failure and a crash, you need coverage that explicitly includes completed operations. Confirm your policy doesn't exclude calibration work.
General Liability vs. Garagekeepers Insurance
General liability covers third-party injuries and property damage tied to your business. A customer slipping on glass shards in your waiting area or a mobile tech cracking a homeowner's driveway falls here.
Garagekeepers covers customer vehicles in your care, custody, or control. The catch is that general liability almost always excludes those vehicles. Many owners assume they're protected until a $70,000 BMW X5 gets keyed in their lot overnight.
Garagekeepers comes in three forms:
- Legal liability: pays only if you're found negligent
- Direct primary: pays regardless of fault, on a primary basis
- Direct excess: pays regardless of fault, but only after the customer's own auto policy
Direct primary costs more but protects customer relationships. Nobody wants to tell a loyal client to file against their own insurance.
Protecting Your Physical Assets and Business Income
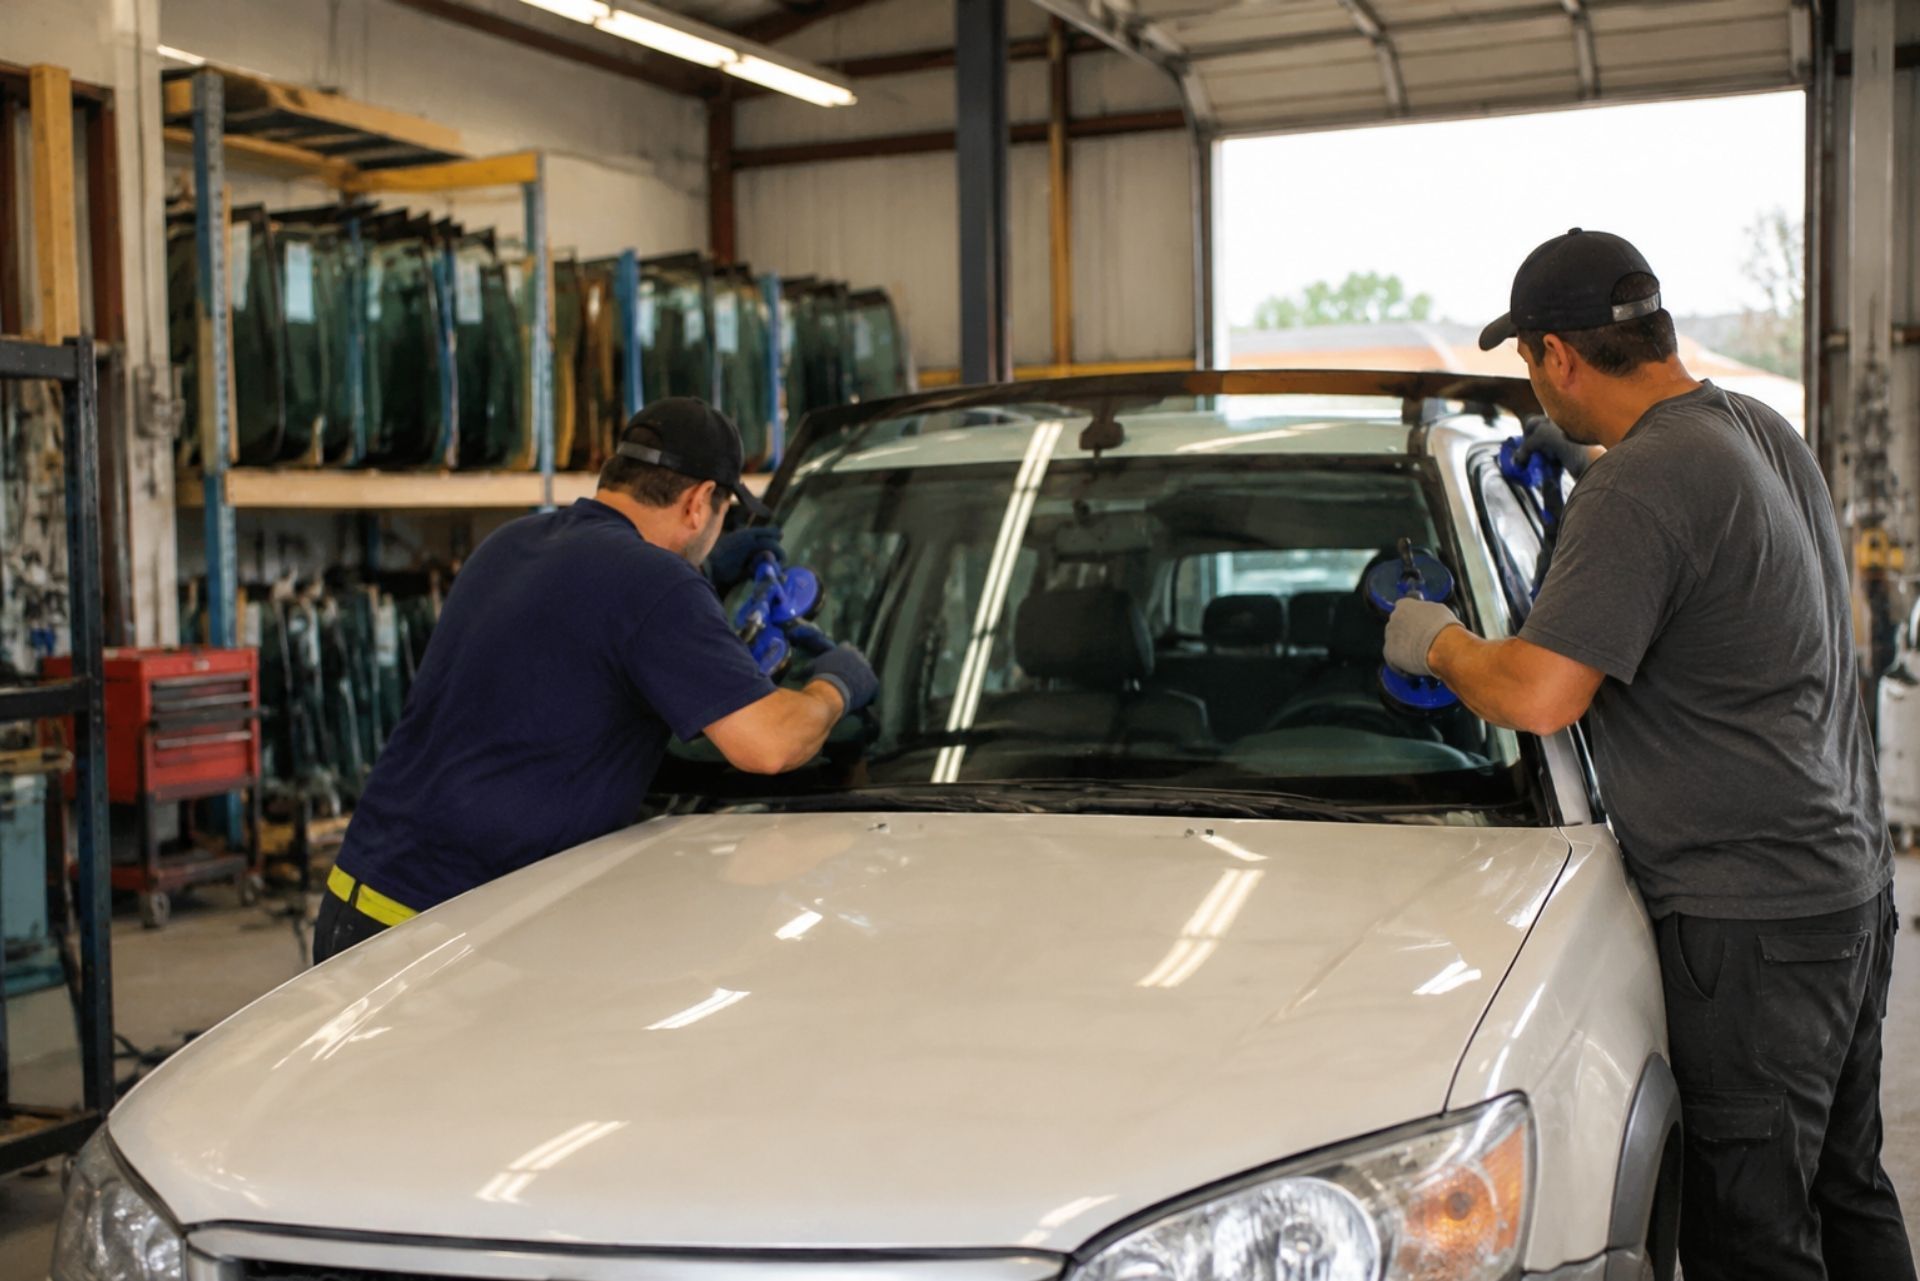
Your building, glass inventory, calibration rigs, and service vans represent serious money. A single ADAS calibration system can cost as much as a new truck, and replacement glass for late-model vehicles isn't cheap to restock.
Texas shops face specific threats. North Texas sees some of the costliest hail in the country, coastal shops deal with named storms, and freezes like the 2021 winter storm burst pipes statewide. Theft of catalytic converters and tools from vans is also common in major metros.
A practical starting point for many owners is a Business Owner's Policy. Texas auto repair shops typically pay $800 to $2,500 a year for a BOP as of late 2026, bundling property and general liability. That said, BOPs often cap property limits and may not fit shops with expensive calibration equipment.
Commercial Property and Business Interruption
Commercial property pays to repair or replace your building and contents. Pay attention to valuation. Actual Cash Value subtracts depreciation, so a five-year-old calibration rig might pay out at half its replacement price. Replacement Cost pays what it takes to buy new equipment today, which is almost always worth the higher premium.
Business interruption covers lost income and ongoing expenses when a covered event shuts you down. If a hail-damaged roof closes your bay for six weeks, it pays rent, payroll, and lost net profit. One thing to keep in mind: most policies include a 72-hour waiting period before coverage kicks in.
Ask about extra expense coverage too. It pays for temporary space or added mobile service so you keep customers during repairs.
Here's how the main policies stack up for a typical Texas glass operation:
| Coverage | What It Protects | Common Gap | Who Needs It |
|---|---|---|---|
| General Liability | Third-party injury and damage | Excludes customer vehicles | Every shop |
| Garagekeepers | Customer cars in your care | Legal liability form needs proof of fault | Shops storing vehicles |
| Commercial Property | Building, glass, tools | ACV valuation shortchanges claims | Shops with a location |
| Business Interruption | Lost income, fixed costs | Waiting periods, low limits | Storm-exposed areas |
| Commercial Auto | Service vans and trucks | Personal auto won't cover business use | Mobile techs |
| Inland Marine | Tools and equipment in transit | Often missing entirely | Mobile installers |
Commercial auto deserves extra attention this year. Texas regulators confirmed
commercial automobile rates will rise 4.9% overall, while private passenger rates climb 2.8%, effective November 1, 2026. Separately, TAIPA
approved a 4.9% increase for commercial automobile liability rates on the same date. If you run a mobile fleet, budget for higher renewals.
Common Questions About Texas Auto Glass Insurance
Does Texas require auto glass shops to carry insurance? Texas requires liability coverage on any vehicle you drive, including service vans. General liability and garagekeepers aren't state-mandated, but landlords, dealerships, and insurance networks often require them.
Will my personal auto policy cover my mobile repair van? Usually not. Personal policies exclude regular business use, so a crash on a service call could leave you uncovered.
What if a windshield I installed fails months later? That falls under completed operations coverage within general liability. Confirm your policy includes it and that calibration work isn't excluded.
How fast should I report a claim? Notify your insurer within 24 to 72 hours. Submit photos, work orders, invoices, and any police or weather reports.
Is workers' comp required in Texas? No, Texas is the only state where most private employers can opt out. Opting out leaves you open to employee injury lawsuits, so most shops buy it.
Making the Right Choice for Your Shop
The right insurance for a Texas auto glass shop isn't one policy. It's a stack: general liability for your work, garagekeepers for customer cars, property and business interruption for your location, and commercial auto for your vans.
Avoid these common mistakes:
- Don't assume general liability covers customer vehicles
- Don't choose Actual Cash Value on expensive calibration equipment
- Don't skip business interruption in hail or hurricane zones
- Don't let mobile techs drive on personal auto policies
- Don't wait until renewal to plan for the November 2026 rate increase
You can check the latest rule changes on the
Texas Department of Insurance bulletin page. Then sit down with an independent agent who knows auto service risks, review your current policies line by line, and close the gaps before the next storm shows up.
About The Author: Aaron Husman
As COO of The Phoenix Insurance, I’m focused on building lasting client relationships and delivering insurance solutions that make protection simple and effective. With years of experience in commercial and personal insurance, I take pride in helping individuals and businesses find coverage that brings confidence and peace of mind.
customer reviews
See What Our Clients Say About Us
Types of Auto Insurance
Insurance For Car Collectors By Car Collectors
Our team specializes in providing tailored insurance coverage for car collectors. Whether you own a rare classic, an exotic beauty, or a powerful muscle car, we understand the unique needs of your collection and work to ensure it’s protected with the care and expertise it deserves.



Contact us for better help and services. Explore all types of car insurance
FREQUENTLY ASKED QUESTIONS
At The Phoenix Insurance, we’re committed to answering your most pressing questions to ensure you feel confident about your coverage. From understanding the benefits of working with an independent agency to the specific insurance options we offer for Texas residents, we’ve got you covered.
What makes The Phoenix Insurance different from other insurance providers?
The Phoenix Insurance is an independent agency, meaning we work with multiple insurance carriers to find the best coverage and rates for your unique needs. Our proactive support and commitment to personalized service set us apart from other providers.
Why should I choose an independent insurance agency in Texas?
Independent agencies like The Phoenix Insurance offer more flexibility and personalized service than large, single-carrier companies. We compare coverage options from top-rated carriers to ensure you get the most value for your money.
Does The Phoenix Insurance provide coverage for real estate investors?
Yes, we specialize in insuring real estate investments, including single-family homes, apartments, commercial buildings, and industrial properties. Our team has extensive experience protecting real estate assets across Texas.
How does The Phoenix Insurance handle claims?
We guide clients through the entire claims process, working directly with the insurance carrier to ensure quick and fair resolutions. Our team is dedicated to providing the support you need when it matters most.
What types of insurance does The Phoenix Insurance offer for Texas residents?
We offer a wide range of personal and business insurance options, including home, auto, umbrella, and recreational vehicle coverage for individuals, as well as liability and property insurance for businesses and real estate investors.
Insurance Knowledge. Stories. Tips.
Our Latest Blogs
Explore expert tips, industry insights, and helpful resources from The Phoenix Insurance to stay informed and make confident decisions about your coverage.


Contact Us