
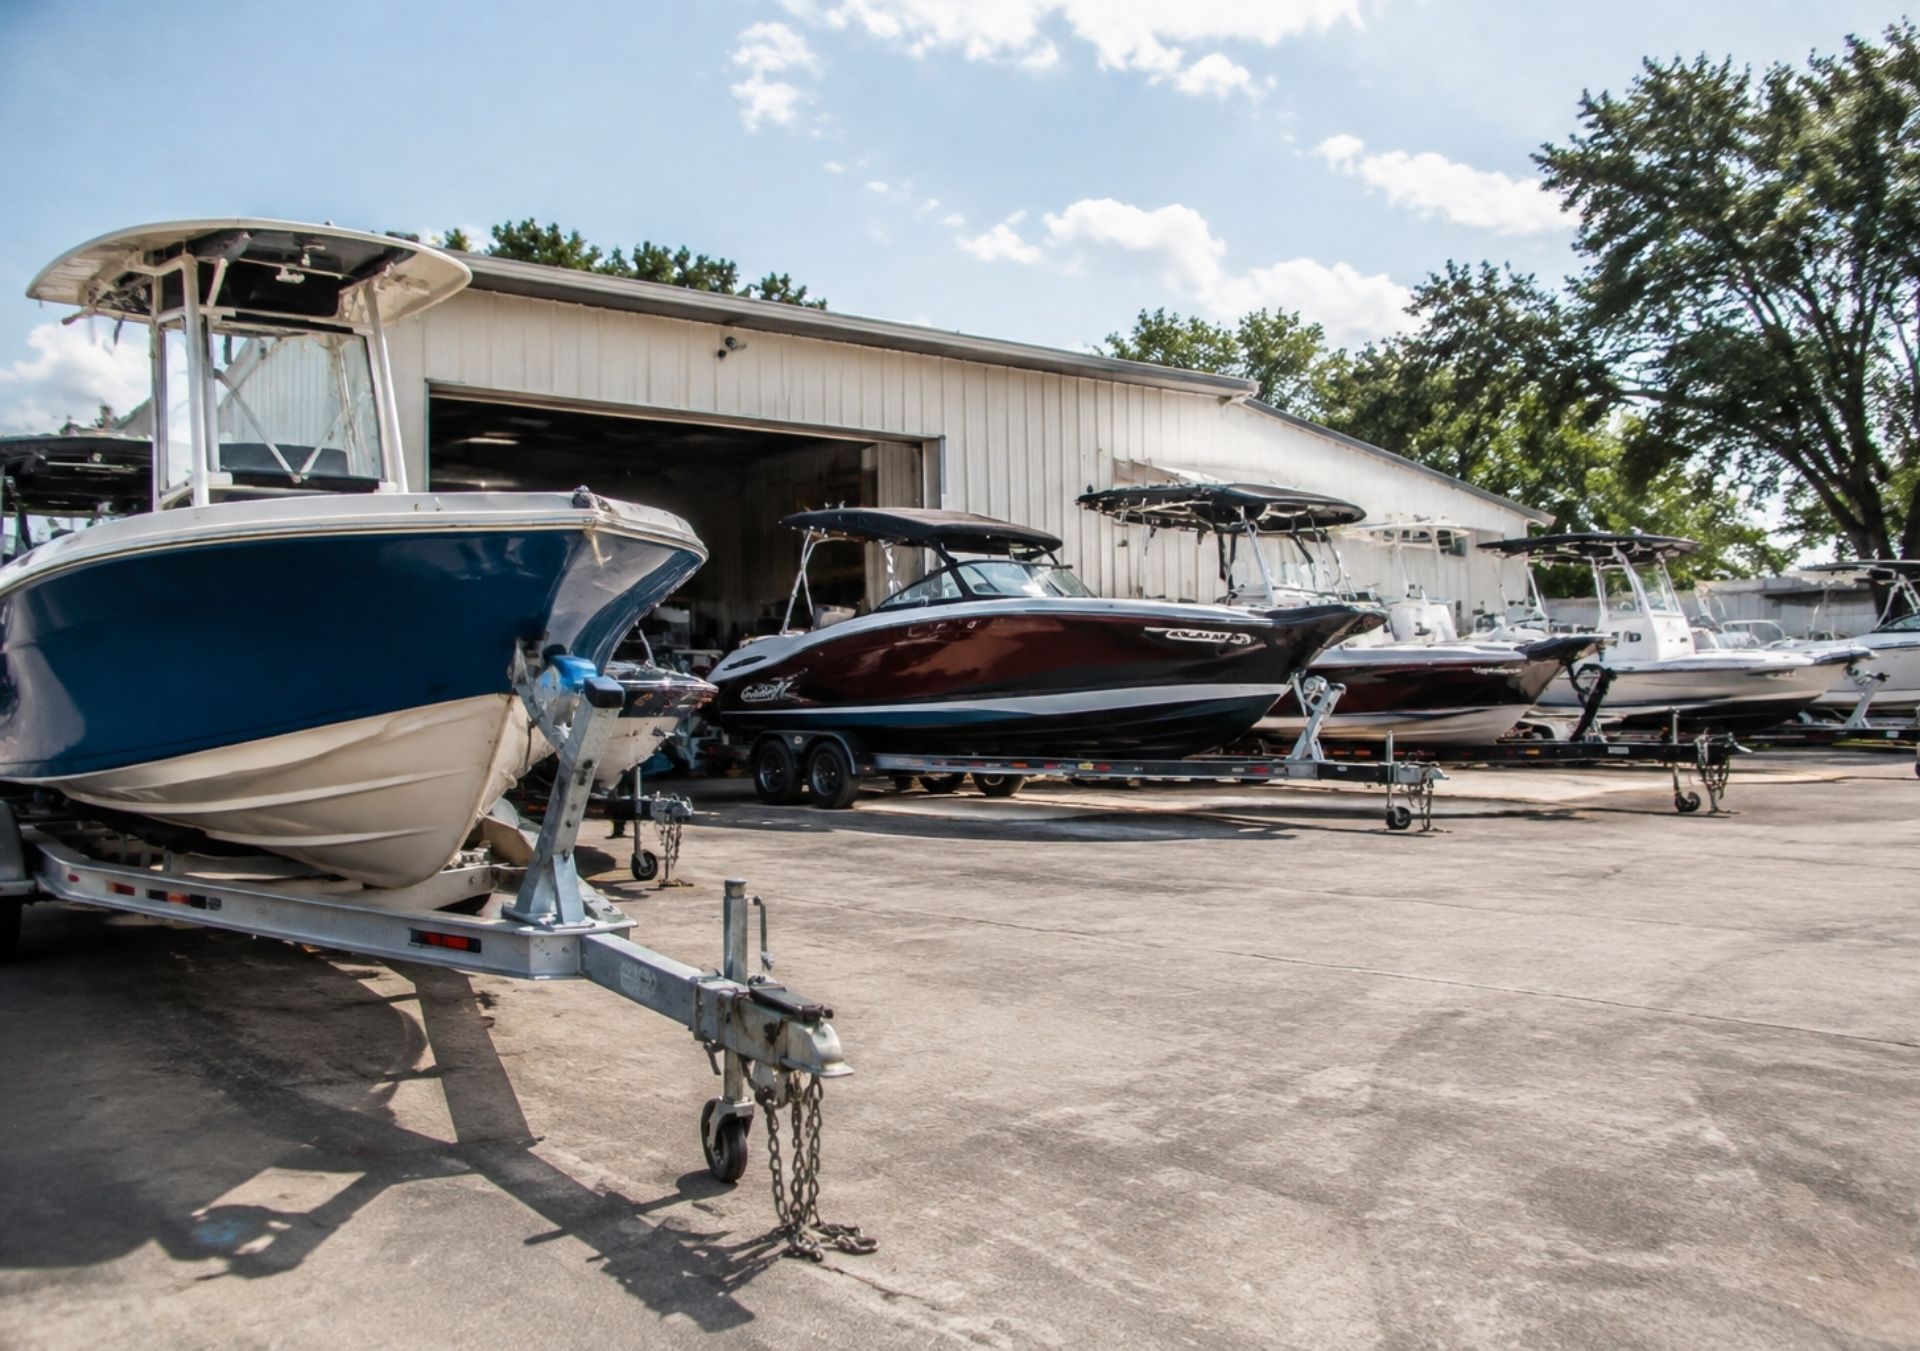
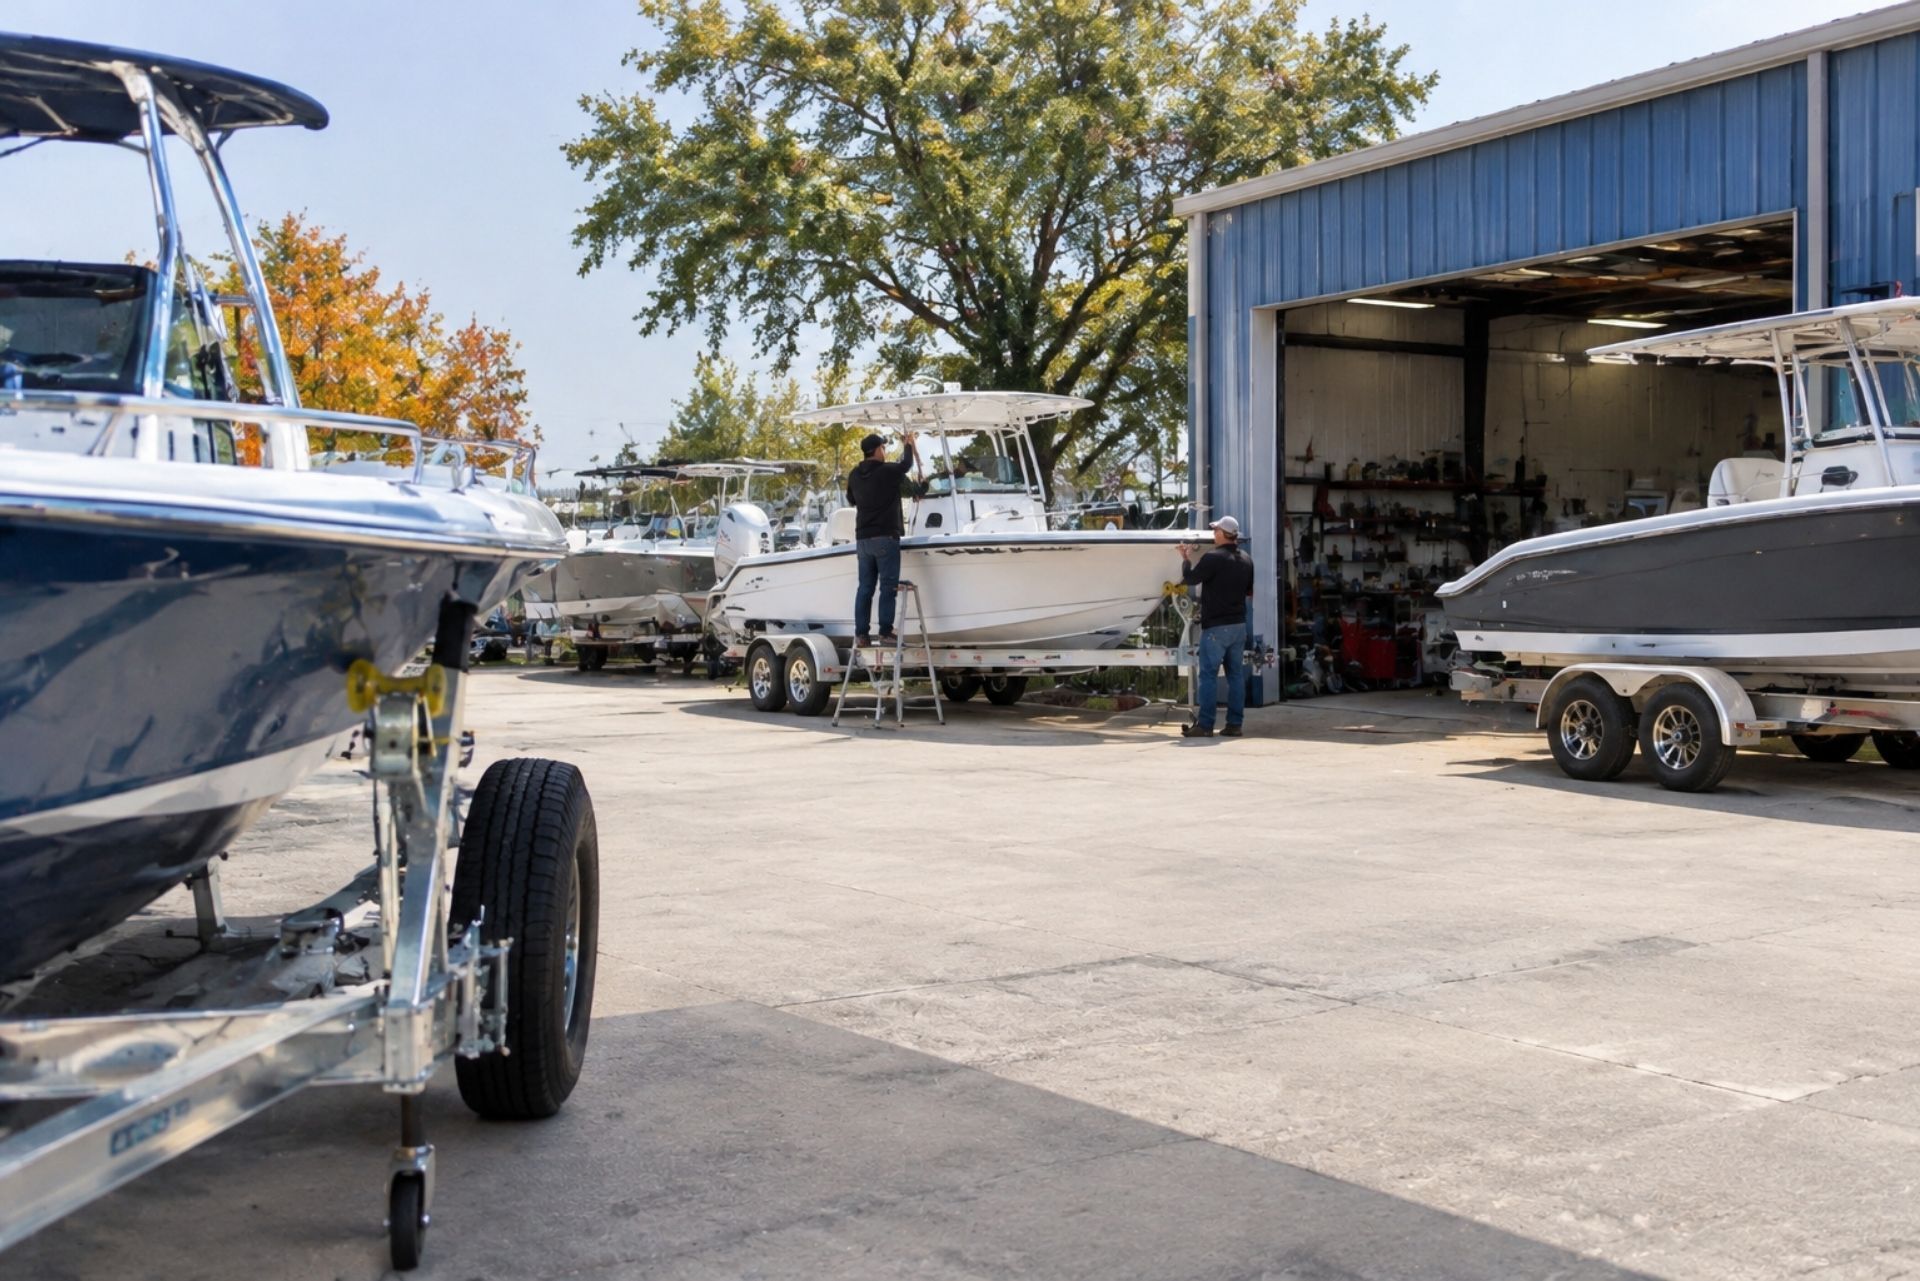
Picture a Saturday in May on Lake Conroe: a customer test-drives a 24-foot wakeboat off your dock, three boats sit in your service bay waiting for impellers, and a thunderstorm is building over Montgomery County. Any one of those moments can turn into a claim, and each one triggers a different part of your policy. This guide to insuring a Texas boat dealership covers liability, property, customer autos, and business interruption. It's written for owners who'd rather find their coverage gaps now than learn about them from an adjuster.
Texas dealers face a mix of risks that inland car lots and coastal marinas rarely share. You have high-dollar floorplan inventory, hurricane and hail exposure, and on-water liability. You may also have a yard full of customer trucks and trailers. If one policy is poorly structured, a single bad week can cost you a season of profit.
Protecting Your Texas Boat Dealership Assets
Your dealership carries two kinds of exposure. One is the damage you cause others. The other is the damage done to what you own. Most underinsured dealers get one of these right and assume it covers the other.
Regulators also set a floor before coverage choices even come into play. Most motor vehicle dealers in Texas must keep a $50,000 surety bond under Tex. Occ. Code Ch. 2301, although dealers that sell only trailers are exempt. A bond isn't insurance, though. It protects your customers, not you, so any claim paid against it comes back to you for repayment.
General Liability vs. Marine Liability
General liability (GL) handles slip-and-falls in your showroom and injuries in the parking lot. It typically excludes watercraft operation, and that exclusion is where dealers get hurt. Say a salesperson runs a demo ride and the boat strikes a swimmer. Your GL carrier will likely deny the claim.
Marine liability, sometimes written as marina operators or dealers' legal liability, fills that gap. It covers demo rides, sea trials, and dock operations. If you rent boats, Texas law adds a requirement. Vessel liveries must buy liability insurance from an insurer licensed in Texas under Parks and Wildlife Code § 31.111. Running even a small rental side business on surplus lines paper can put you out of compliance.
Safeguarding Inventory and Showroom Property
Dealer open lot coverage protects the boats you own or floorplan, whether they're in the showroom, on the lot, or at a boat show in Dallas. Check whether your policy pays Replacement Cost or Actual Cash Value (ACV). Replacement Cost buys a new equivalent. ACV subtracts depreciation, which can shave thousands off the payout on a two-year-old Malibu still sitting in inventory.
Ask about hail sublimits and named storm deductibles too. Gulf Coast policies often set wind deductibles at a percentage of insured value rather than a flat dollar amount.
Commercial property policies for Texas dealerships typically utilize wind/hail deductibles of 1%, 2%, or 5% of the total insured value (TIV). On $3 million of inventory, a 5% deductible means you absorb $150,000 before coverage starts.
Managing Risks for Customer Autos and Watercraft
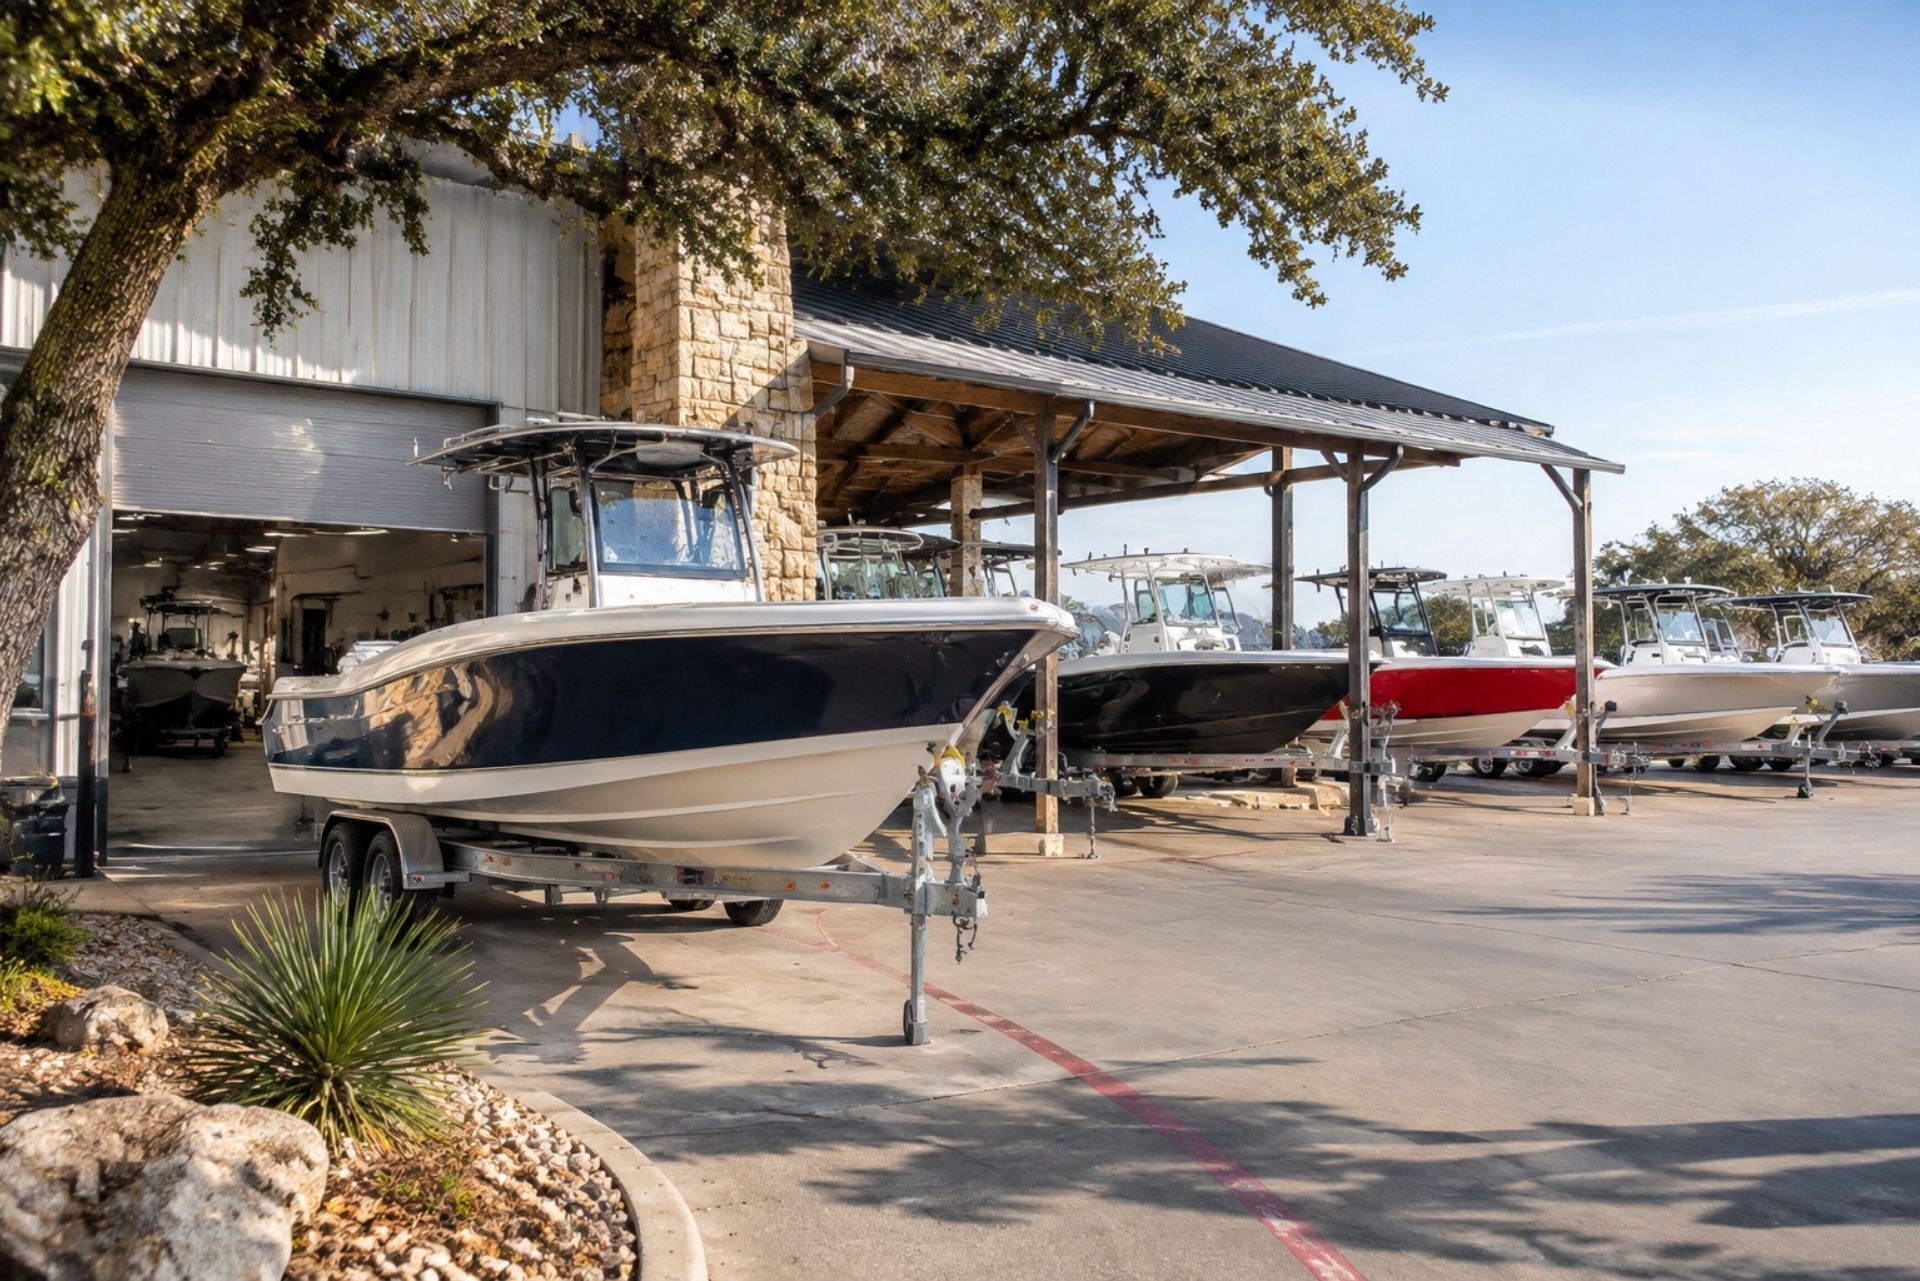
Every customer truck parked in your lot while its owner takes a sea trial is your responsibility. So is every customer boat in your service bay. Your property policy doesn't cover them because you don't own them. Your GL policy usually excludes property in your "care, custody, or control."
Commercial auto adds another layer. When your techs drive a customer's tow vehicle, or deliver a boat with a company truck, you need hired and non-owned auto coverage on top of your owned-vehicle policy. Plan for rising costs. Dealers in Texas commonly see commercial auto renewals climb 8% to 25%, mostly because of large jury verdicts. For dealers placed in the residual market, TAIPA received approval for a 4.9% commercial auto rate increase effective November 1, 2026.
Garagekeepers Coverage for Towed Boats
Garagekeepers coverage protects customer vehicles and boats while you're storing, servicing, or towing them. It comes in three forms:
- Legal liability: pays only if you're at fault. A fire that starts at the neighbor's shop may leave you uncovered.
- Direct primary: pays regardless of fault. This option generates the fewest customer disputes.
- Direct excess: pays only after the customer's own insurance responds.
A typical claim looks like this: a tech jackknifes a customer's 2026 Sea Ray SLX 260 retailing for roughly $174,900 to over $209,000 on I-45 during a pickup. Without garagekeepers, that loss comes straight out of your operating account.
Business Interruption and Weather Risks in Texas
Business interruption coverage replaces lost income and pays ongoing expenses like payroll, rent, and floorplan interest while you rebuild after a covered loss. For Texas dealers, timing makes this coverage critical. A hurricane in September can damage the building, but a slow rebuild that drags into spring costs you your best selling months.
When you review your policy, focus on three details. The waiting period is often 72 hours, and you get no income replacement during it. The period of restoration should be long enough to account for contractor backlogs after a major storm. Extended business income keeps payments going after you reopen while customers trickle back.
Insurers also reward loss prevention. In August 2026, the governor directed TDI to
account for loss-mitigation efforts in rate setting. Document the steps you take, such as backup generators for climate-controlled storage, hurricane evacuation plans that move inventory inland to Waco or Temple, and impact-rated doors. Keep timestamped photos and an inventory log updated in software you can reach from anywhere.
| Coverage | What It Protects | Common Gap |
|---|---|---|
| General Liability | Premises injuries | Excludes on-water operations |
| Marine Liability | Demo rides, docks | Rentals may need a separate policy |
| Dealer Open Lot | Your boat inventory | ACV payout, hail sublimits |
| Garagekeepers | Customer boats and autos | Legal liability form requires fault |
| Commercial Auto | Owned and hired vehicles | Non-owned autos often left off |
| Business Interruption | Lost income, payroll | Short restoration period |
Dealer "don'ts" checklist:
- Don't let unlicensed staff run sea trials.
- Don't assume floorplan lender insurance protects your equity.
- Don't skip reporting a claim. Notify your carrier within 24 to 72 hours, with photos and repair orders.
- Don't leave inventory values outdated. Update them quarterly.
- Don't buy rental liability from a carrier that isn't licensed in Texas.
Common Questions About Boat Dealer Insurance
Do I need marine liability if I already have general liability? Yes, if you run demo rides or operate docks. GL policies usually exclude watercraft operation, so on-water accidents go uncovered.
What happens if my insurer drops me? Starting January 1, 2026, Texas law requires insurers to give a written explanation for any declination, cancellation, or non-renewal. Use that explanation to fix the issue before you shop for a new policy.
Does my policy cover boats at a boat show? Only if your dealer open lot or inland marine form includes off-premises and transit coverage. Confirm it in writing before the Houston show.
Is the surety bond the same as insurance? No. The bond protects customers, and you have to repay any claim paid against it.
How often should I update inventory values? Update them at least quarterly, and right after peak-season deliveries.
Insurance for a Texas boat dealer works best when you treat each risk separately. You need liability for both the showroom and the water, property coverage that pays replacement cost, garagekeepers protection for every customer truck and trailer, and business interruption coverage long enough to outlast a slow post-hurricane rebuild. Rates are climbing, especially on commercial auto, so documented loss prevention now affects your premium directly.
Start by pulling your current declarations pages and comparing them against the table above. Mark any line where you're relying on legal liability garagekeepers, ACV valuation, or a restoration period of 90 days or less. Then sit down with an agent who writes marine dealer business in Texas and work through each gap. Do this review before storm season, so you're not finding gaps after a storm has already hit.
About The Author: Aaron Husman
As COO of The Phoenix Insurance, I’m focused on building lasting client relationships and delivering insurance solutions that make protection simple and effective. With years of experience in commercial and personal insurance, I take pride in helping individuals and businesses find coverage that brings confidence and peace of mind.
customer reviews
See What Our Clients Say About Us
Types of Auto Insurance
Insurance For Car Collectors By Car Collectors
Our team specializes in providing tailored insurance coverage for car collectors. Whether you own a rare classic, an exotic beauty, or a powerful muscle car, we understand the unique needs of your collection and work to ensure it’s protected with the care and expertise it deserves.



Contact us for better help and services. Explore all types of car insurance
FREQUENTLY ASKED QUESTIONS
At The Phoenix Insurance, we’re committed to answering your most pressing questions to ensure you feel confident about your coverage. From understanding the benefits of working with an independent agency to the specific insurance options we offer for Texas residents, we’ve got you covered.
What makes The Phoenix Insurance different from other insurance providers?
The Phoenix Insurance is an independent agency, meaning we work with multiple insurance carriers to find the best coverage and rates for your unique needs. Our proactive support and commitment to personalized service set us apart from other providers.
Why should I choose an independent insurance agency in Texas?
Independent agencies like The Phoenix Insurance offer more flexibility and personalized service than large, single-carrier companies. We compare coverage options from top-rated carriers to ensure you get the most value for your money.
Does The Phoenix Insurance provide coverage for real estate investors?
Yes, we specialize in insuring real estate investments, including single-family homes, apartments, commercial buildings, and industrial properties. Our team has extensive experience protecting real estate assets across Texas.
How does The Phoenix Insurance handle claims?
We guide clients through the entire claims process, working directly with the insurance carrier to ensure quick and fair resolutions. Our team is dedicated to providing the support you need when it matters most.
What types of insurance does The Phoenix Insurance offer for Texas residents?
We offer a wide range of personal and business insurance options, including home, auto, umbrella, and recreational vehicle coverage for individuals, as well as liability and property insurance for businesses and real estate investors.
Insurance Knowledge. Stories. Tips.
Our Latest Blogs
Explore expert tips, industry insights, and helpful resources from The Phoenix Insurance to stay informed and make confident decisions about your coverage.


Contact Us